
Bond Market to the Fed: We’re Not Buying the “Mission Accomplished” Story
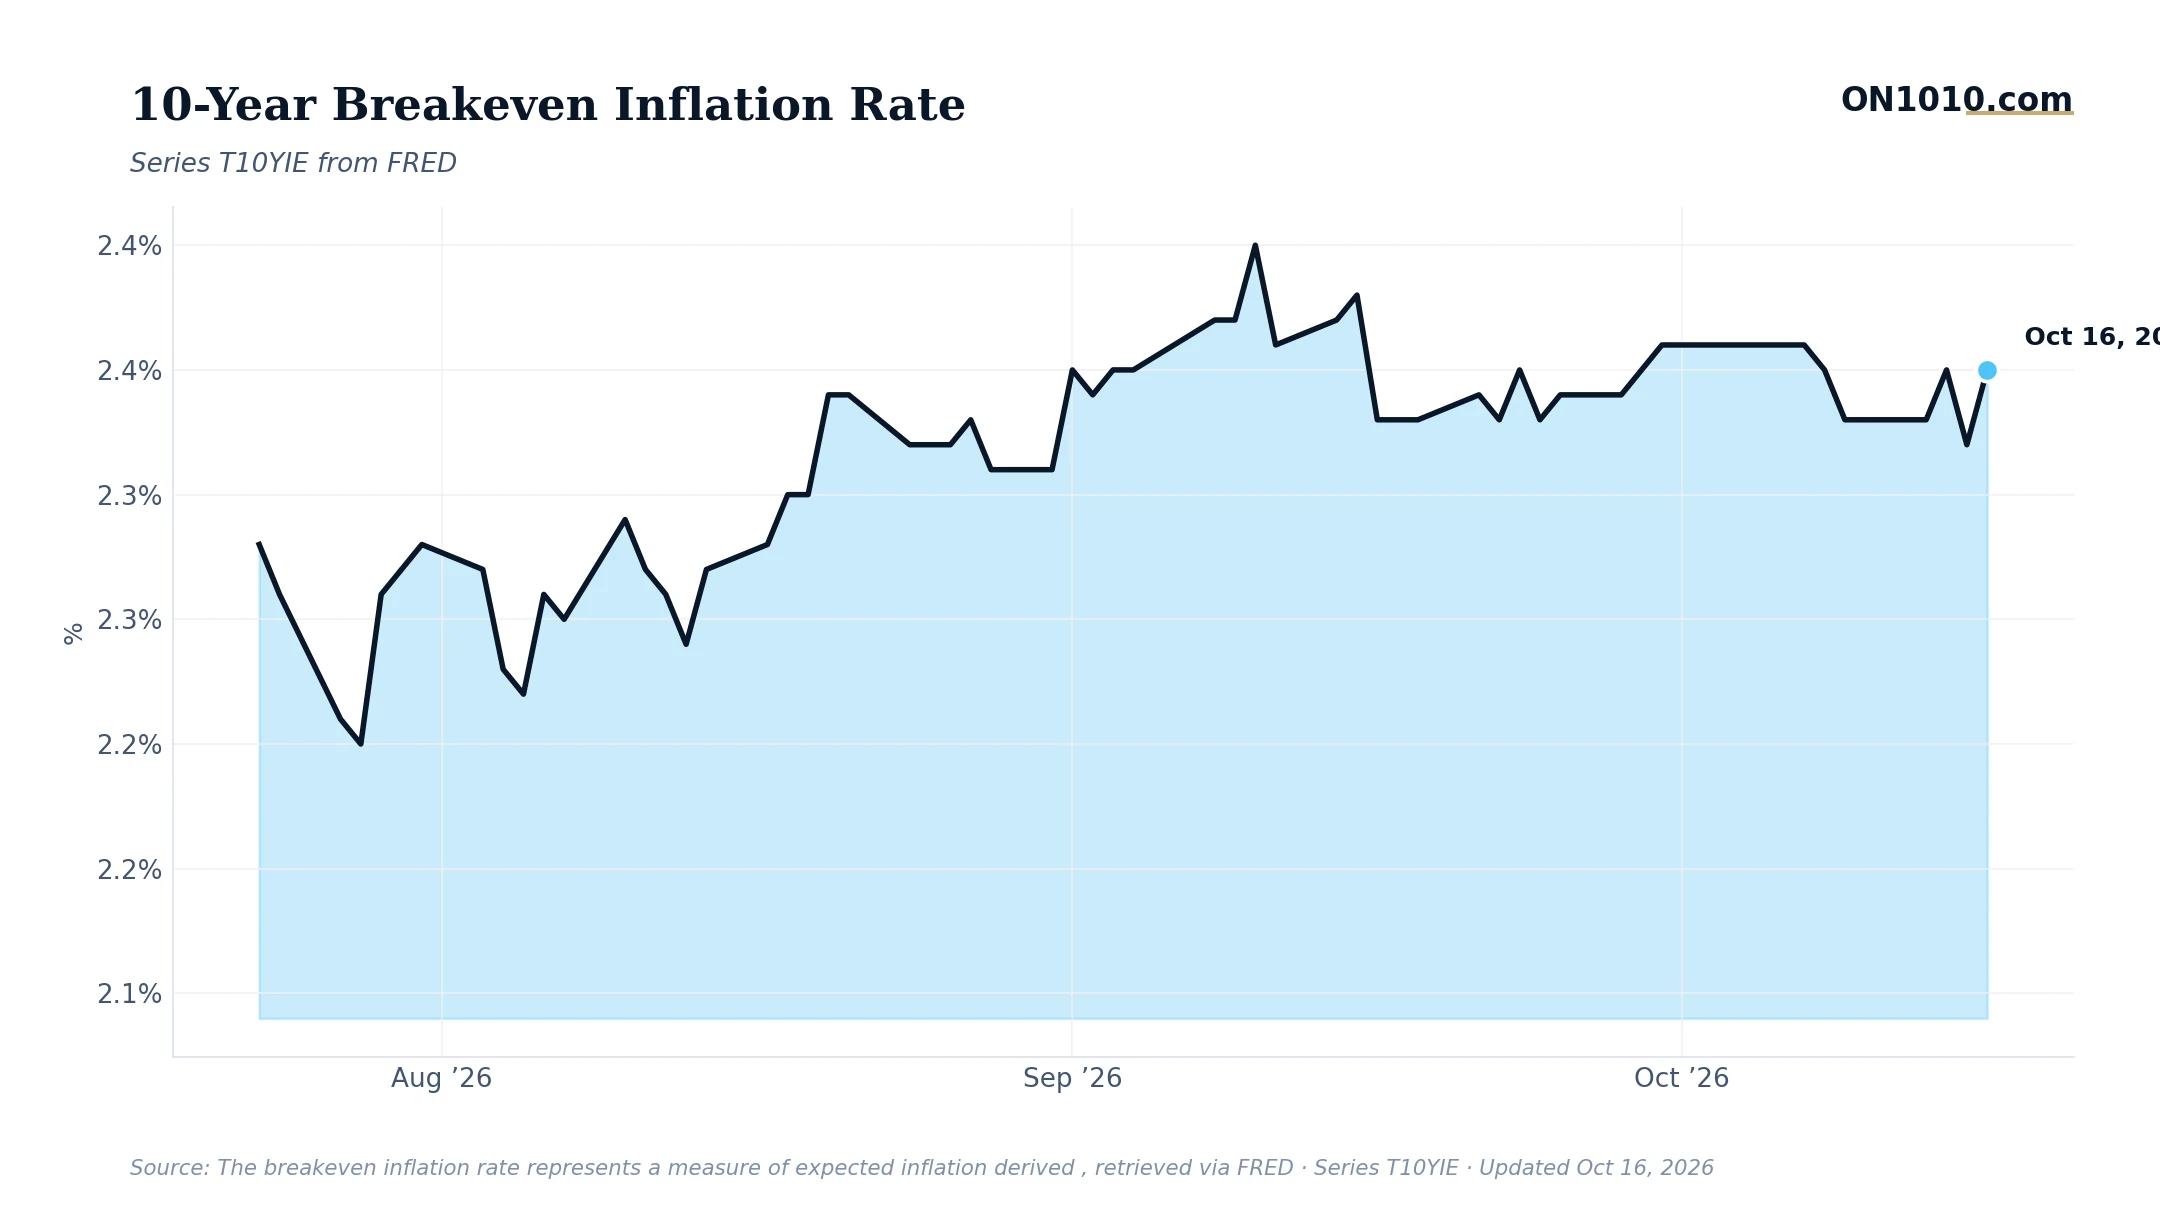
The 10-year breakeven inflation rate ticked up to 2.35% on Friday, sitting in a narrow range it has barely left all week. Between 2.32% and 2.35% for seven straight trading days. That kind of stability in a noisy environment is itself a signal worth examining.
Breakevens are what you get when you subtract the yield on inflation-protected Treasuries (TIPS) from the yield on regular Treasuries. The gap represents what the bond market collectively expects inflation to average over the next decade. At 2.35%, that expectation is above the Fed’s 2% target and has been for most of this cycle.
The broader backdrop makes that number more interesting. Core inflation is still running hot relative to history. The real policy rate (what the Fed charges minus what inflation is doing) is restrictive, meaning the Fed has its foot on the brake. And yet bond traders are pricing in inflation that stays meaningfully above target for the next ten years. That is the market telling you it does not fully trust that the current stance will hold, or that the fight is finished.
Historically, when breakevens have anchored above the Fed’s target even during a period of tight policy, it has often reflected one of two things: either lingering doubt about the central bank’s willingness to keep rates high long enough, or structural forces (supply chains, reshoring, fiscal spending) that the market thinks will keep prices elevated regardless. Both explanations have been discussed in this cycle. The honest answer is that the data has not yet clearly picked a winner.
For business leaders and capital allocators, in past cycles, persistently elevated breakevens alongside tight monetary policy have raised questions about the timing of any policy pivot. When the market prices in above-target inflation for a decade, it tends to keep long-term borrowing costs elevated as well. That has consequences for financing decisions, valuations, and how long “higher for longer” actually lasts in practice.
Bottom Line: The bond market is not expecting an inflation problem, but it is not expecting a clean resolution either. At 2.35%, breakevens are saying: close enough to feel comfortable, far enough from 2% to keep watching.
Source: Federal Reserve Economic Data (FRED)
ON1010 Research is an independent publisher of economic education and is not a registered investment adviser, broker-dealer, or investment company. This content is for educational and informational purposes only and is not investment advice or a recommendation to buy, sell, or hold any security. Published under the publisher exemption recognized by Section 202(a)(11)(D) of the Investment Advisers Act of 1940 (Lowe v. SEC). Always consult a qualified financial professional before making any financial decision.
Free Research
The economy moves fast. We make sure you move faster.
Economic data, policy shifts, and market signals — delivered to your inbox.
Subscribe Free