
Economic Wire: Stock investors are ready to move on from the AI rout. Credi
When Stocks Shrug and Bonds Don’t: The AI Credit Stress Story Wall Street Is Glossing Over
According to CNBC, investors are still demanding elevated yields and increased default insurance on bonds issued by CoreWeave and Oracle, even as equity markets attempt to shake off recent AI-related turbulence. The divergence is the story. Stocks move on narratives; bonds move on cash flow math.
Credit markets are the economy’s balance sheet, and right now they are telling a different story than the equity tape. When bond investors demand a higher yield or pay up for credit default protection, they are pricing the probability that a borrower cannot service its debt. That is a fundamentals question, not a sentiment question. For CoreWeave in particular, the concern is structural: the business requires massive, continuous capital expenditure to build and maintain AI infrastructure, which means its debt load is large and its free cash flow, at least in early stages, is thin. Oracle carries different risk but a related one: large AI commitments mean large financing needs, and in a high-rate environment, rolling that debt gets more expensive over time.
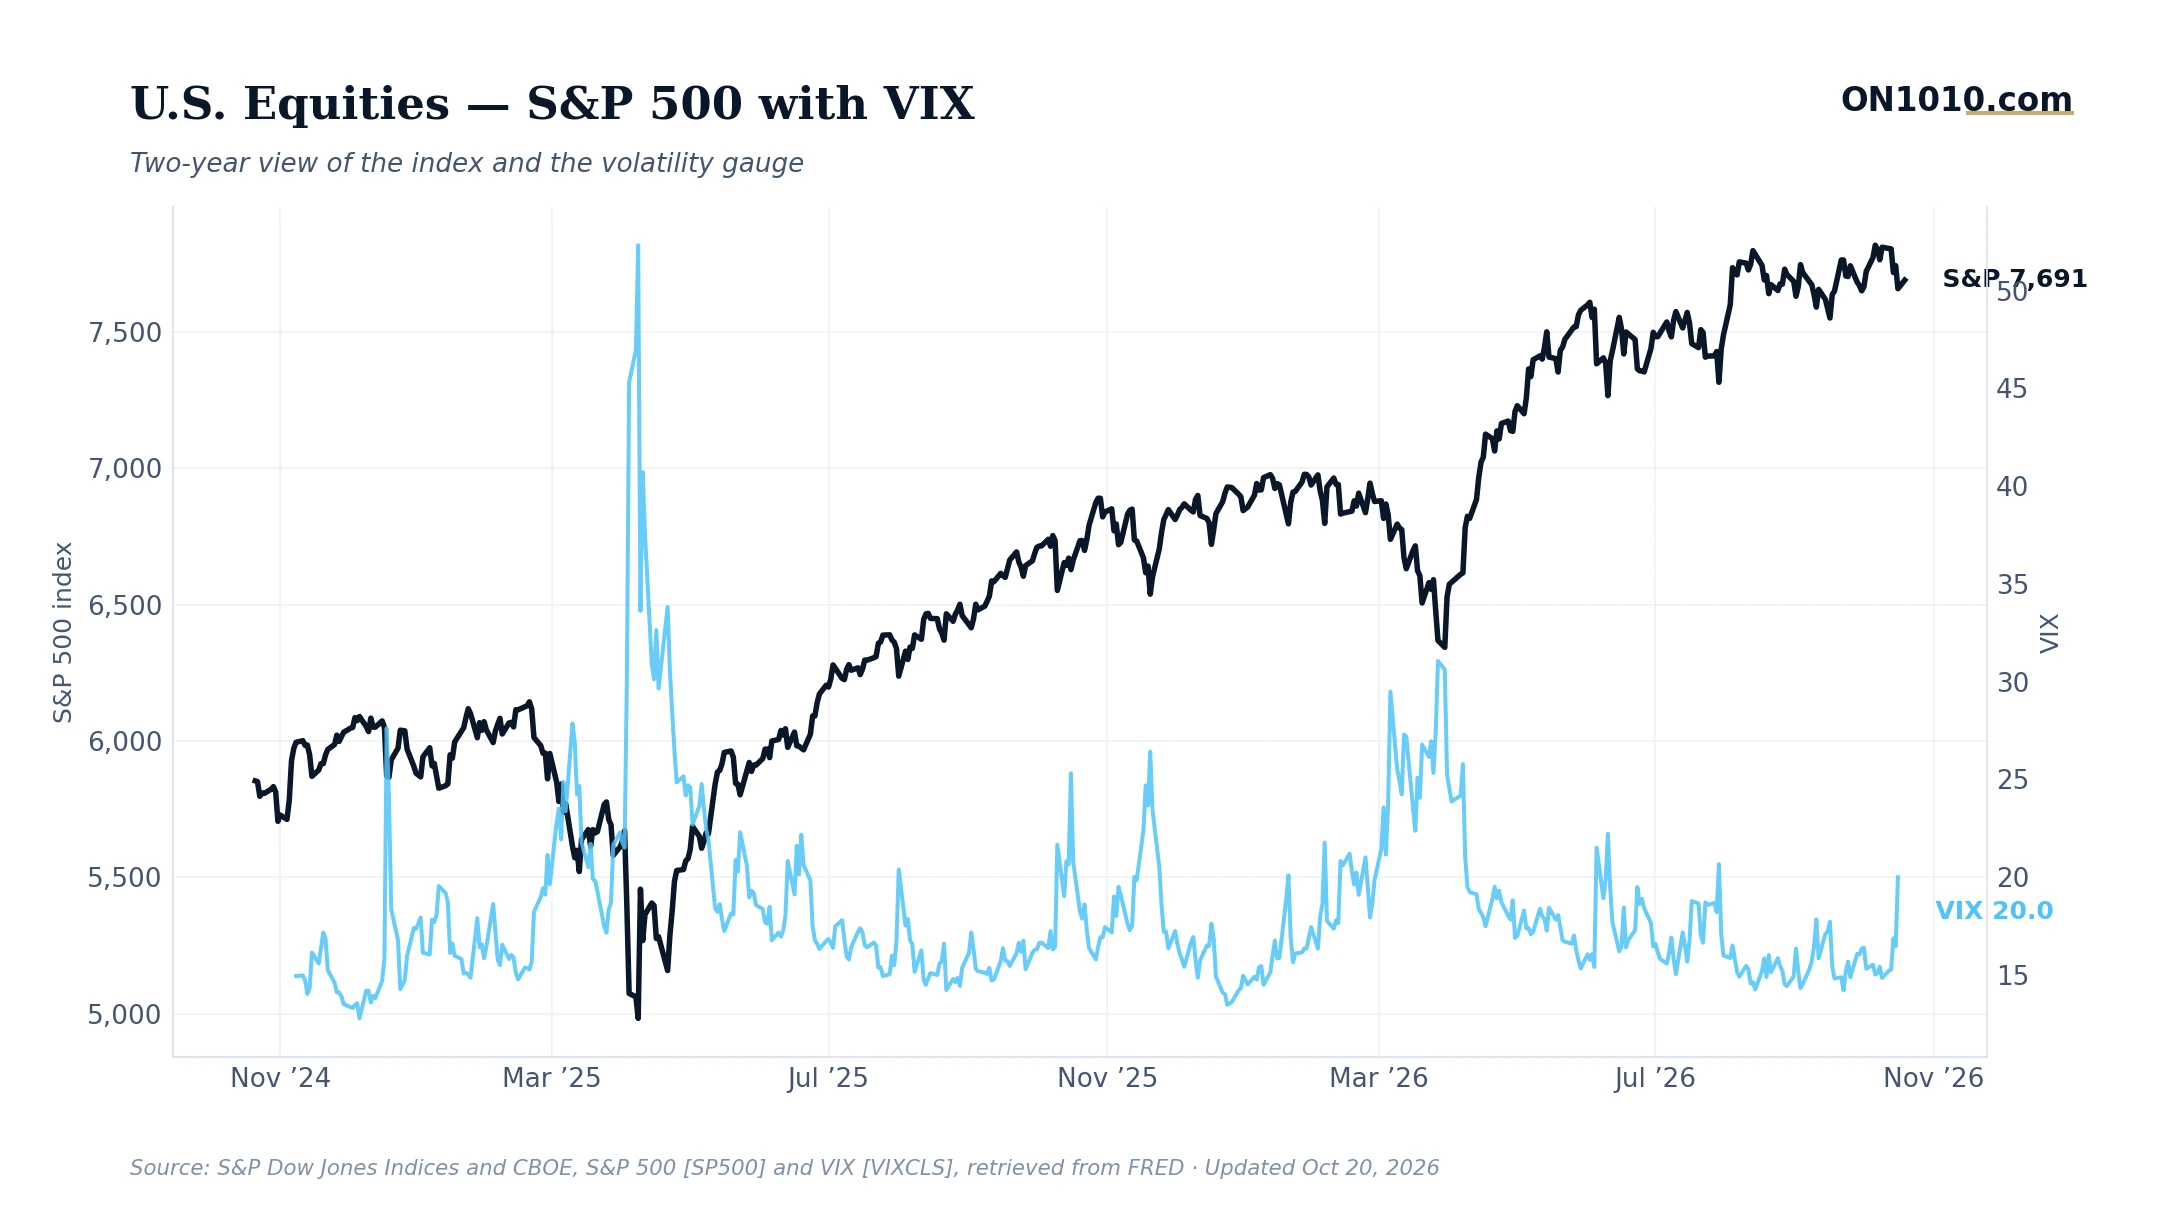
The backdrop makes this harder to dismiss. Credit conditions are sitting in the upper quarter of their historical range and have moved wider recently, not tighter. That is a signal worth taking seriously. Historically, investors have paid close attention when credit spreads widen even as equity markets stabilize, because credit often reprices risk several months before earnings show the problem. The bond market’s job is to answer one question: do these companies generate enough cash to pay me back? When the answer gets harder to calculate, spreads go up first.
Sector rotation is reinforcing the same message. Consumer Staples and Health Care are outperforming the broader market by meaningful margins, while Technology is lagging. That is the market’s posture, not its prediction, but the posture rhymes with what bond investors are pricing.
Bottom Line: Equity markets can run on optimism; credit markets run on math. When they diverge on the same company, the bond market has historically been the more reliable early warning system.
Read more: CNBC Top News
ON1010 Research is an independent publisher of economic education and is not a registered investment adviser, broker-dealer, or investment company. This content is for educational and informational purposes only and is not investment advice or a recommendation to buy, sell, or hold any security. Published under the publisher exemption recognized by Section 202(a)(11)(D) of the Investment Advisers Act of 1940 (Lowe v. SEC). Always consult a qualified financial professional before making any financial decision.
Free Research
The economy moves fast. We make sure you move faster.
Economic data, policy shifts, and market signals — delivered to your inbox.
Subscribe Free