
Inflation Is Picking Up Again. The Fed Just Lost Room It Didn’t Have Much Of.
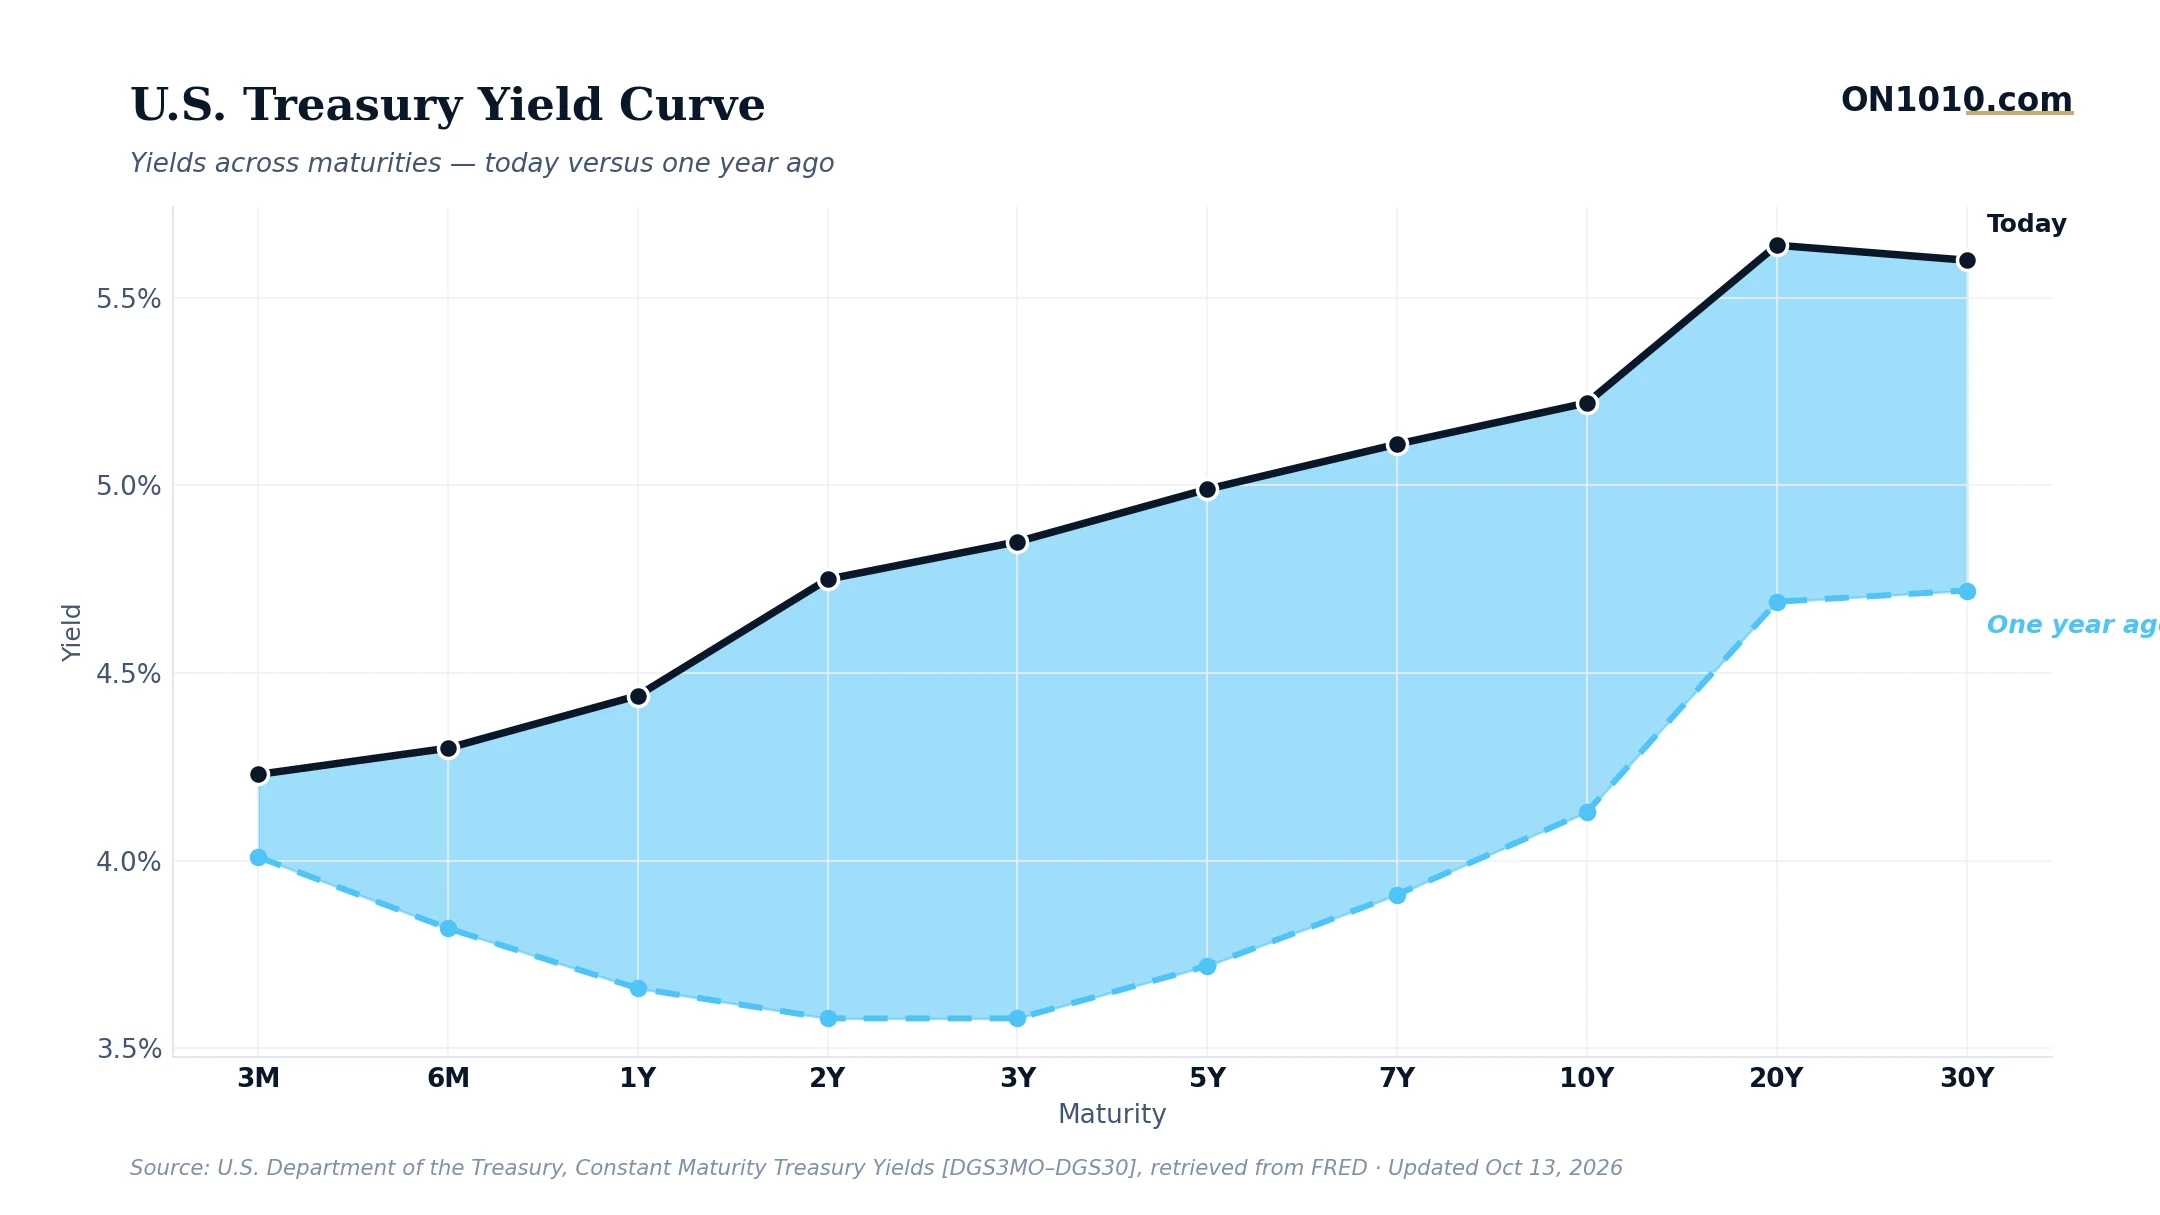
According to CNBC, economists expect September’s Consumer Price Index to show prices rising 0.6% for the month and 3.6% year over year. That monthly number is the part worth watching closely. Annualize 0.6% monthly gains and you get something closer to 7%, which is nowhere near where the Fed needs this story to go.
The uncomfortable reality is that inflation was already running hot relative to its own history coming into this print, and now it appears to be reaccelerating. The Fed’s policy rate sits well above its historical midpoint, meaning monetary policy is already restrictive on paper. But restrictive policy and falling inflation are two different things. When inflation starts climbing again while rates are already high, the Fed faces a shrinking set of options, and the economy faces the cost of holding those rates higher for longer than markets may have priced.
This is where the real vs. nominal distinction cuts deepest. Businesses that borrowed or planned based on an assumption that inflation was on a steady downward path now face a different arithmetic. Profit margins get squeezed from two directions: input costs stay elevated, and any workers who negotiated raises tied to past inflation expectations now cost more in real terms than firms anticipated. That margin pressure tends to show up in hiring and investment decisions before it shows up in headline earnings.
Long-term interest rates are already historically high, and credit spreads are wide, signaling stress in lending markets. Historically, investors have paid close attention to how the bond market prices a CPI surprise like this one. When inflation expectations become unanchored, even modestly, bond investors have tended to demand higher yields to compensate, which pushes borrowing costs up across the economy and tightens financial conditions beyond what the Fed explicitly controls. The question worth asking now is whether this is a one-month blip driven by energy or shelter, or whether the underlying trend has genuinely shifted.
Bottom Line: A 0.6% monthly CPI reading reframes the conversation from “when does the Fed cut?” to “how long do rates stay here?” and those are very different environments for businesses planning capital commitments and investors pricing assets.
Read more: CNBC Economy
ON1010 Research is an independent publisher of economic education and is not a registered investment adviser, broker-dealer, or investment company. This content is for educational and informational purposes only and is not investment advice or a recommendation to buy, sell, or hold any security. Published under the publisher exemption recognized by Section 202(a)(11)(D) of the Investment Advisers Act of 1940 (Lowe v. SEC). Always consult a qualified financial professional before making any financial decision.
Free Research
The economy moves fast. We make sure you move faster.
Economic data, policy shifts, and market signals — delivered to your inbox.
Subscribe Free