
Nike’s Real Problem Isn’t China. It’s Margins.
According to CNBC, Nike is expected to report another quarter of declining sales when it posts earnings after the bell today, with the turnaround effort still in early innings and China recovery nowhere near complete. The headline will focus on whether revenues beat or miss by a few percentage points. The more important number is what’s happening to margins.
Nike’s fundamental challenge is a cost structure built for a growth company that has temporarily stopped growing. When revenue falls, fixed costs don’t fall with it. That squeeze on operating margins is the signal that matters most, because margins lead everything else: hiring, inventory investment, marketing spend, and ultimately the stock price. A company can survive a bad revenue quarter; compressing margins that persist quarter after quarter tell a different story about competitive positioning.
The China angle deserves honest scrutiny. Consumer sentiment in China has been under pressure from a property-led slowdown, and domestic athletic brands like Anta and Li-Ning have taken real share from Nike in their home market. Winning that share back requires either deeper discounting (which crushes margins further) or genuine product differentiation (which takes years). There is no quick fix, and any guidance suggesting otherwise should be read skeptically.
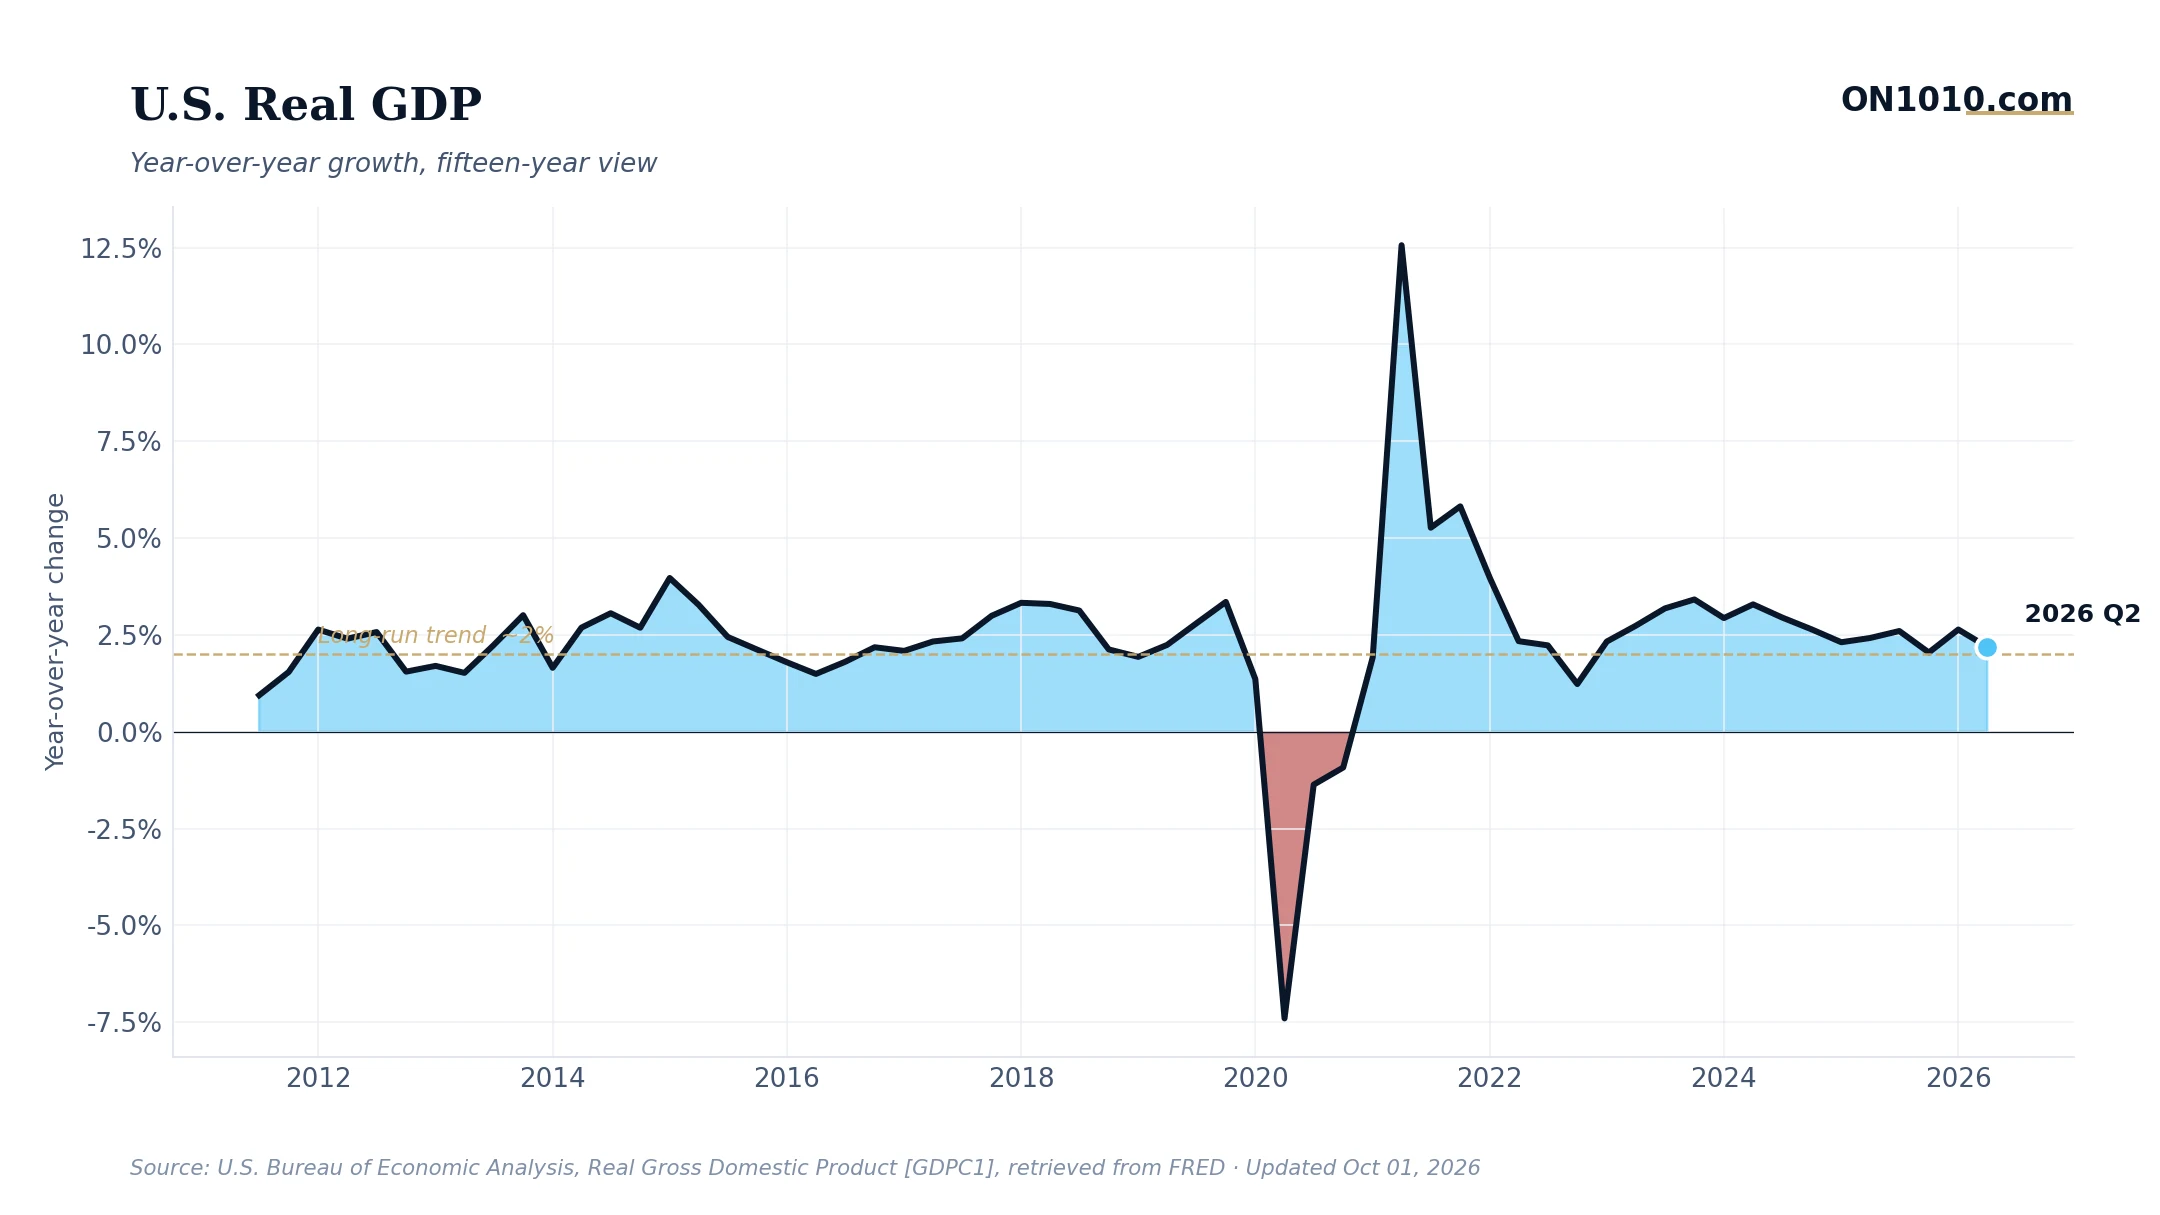
The broader macro backdrop doesn’t make it easier. Consumer sentiment in the U.S. sits near the bottom of its historical range right now, and real rates are high by historical standards. That combination pressures discretionary spending across the board, and premium athletic footwear sits squarely in the discretionary bucket.
Historically, investors have used periods of margin compression at large consumer brands as a test of management credibility: does leadership acknowledge the structural problems and offer a realistic timeline, or do they lean on “we see green shoots” language that buys another quarter? The earnings call transcript often matters as much as the numbers.
Bottom Line: Watch the gross margin line and the China segment revenue, not the headline EPS beat or miss. Those two numbers will tell you whether this is a turnaround in progress or a turnaround still waiting to start.
Read more: CNBC Top News
ON1010 Research is an independent publisher of economic education and is not a registered investment adviser, broker-dealer, or investment company. This content is for educational and informational purposes only and is not investment advice or a recommendation to buy, sell, or hold any security. Published under the publisher exemption recognized by Section 202(a)(11)(D) of the Investment Advisers Act of 1940 (Lowe v. SEC). Always consult a qualified financial professional before making any financial decision.
Free Research
The economy moves fast. We make sure you move faster.
Economic data, policy shifts, and market signals — delivered to your inbox.
Subscribe Free