
The 10-Year Yield Won’t Stop Climbing. Here’s What the Market Is Telling You.
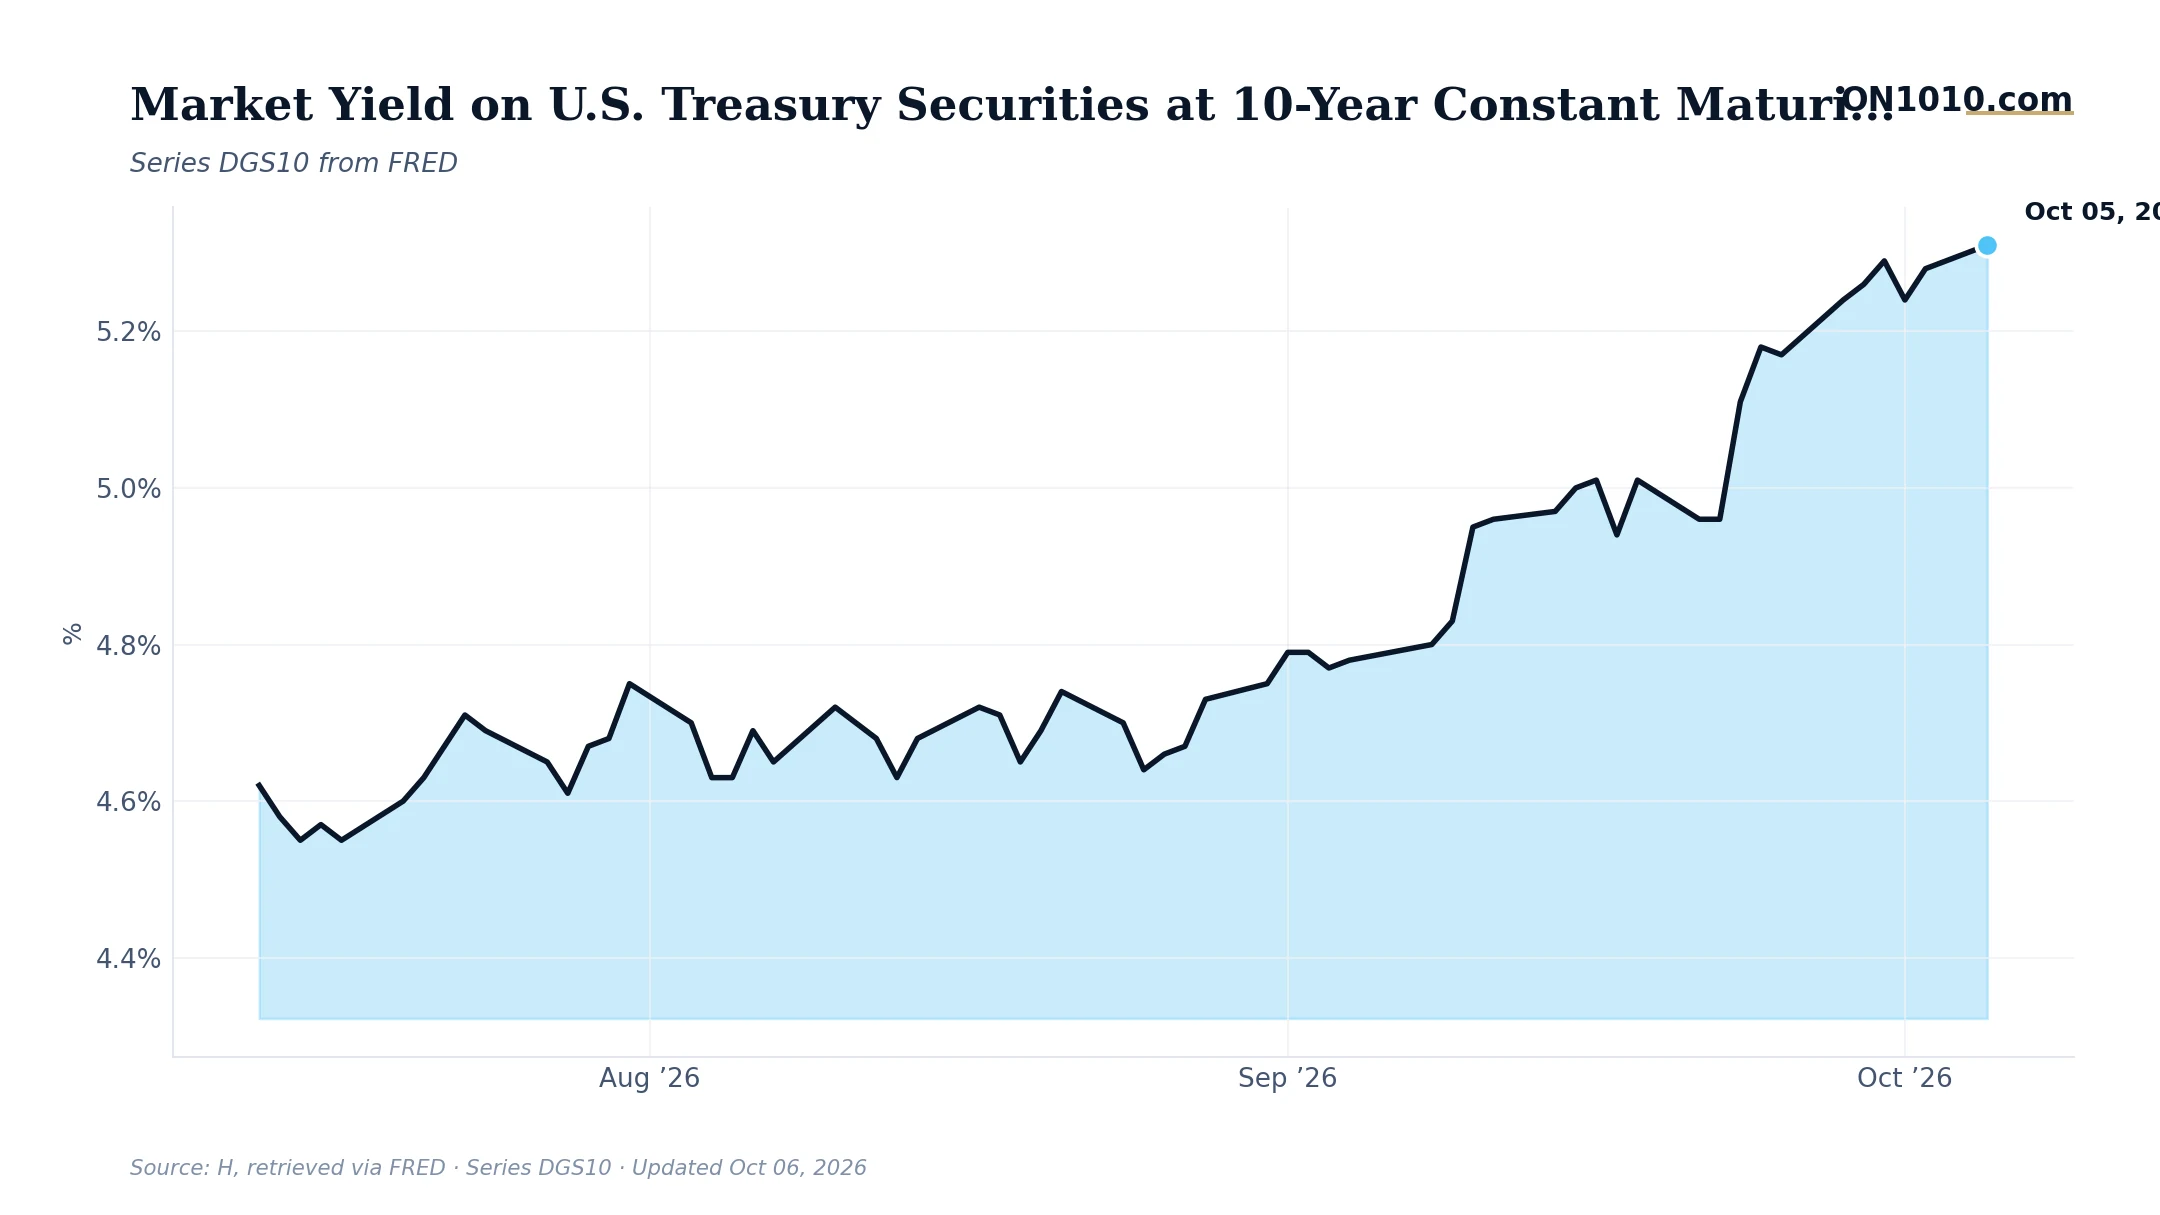
The 10-year Treasury yield hit 5.31% on Monday, its highest point in the recent trend and a level that would have seemed extraordinary just a few years ago. More telling than the single number is the pattern: yields have held between 5.24% and 5.31% for the past two weeks, refusing to retreat despite a monetary policy stance that remains historically tight.
This isn’t a spike. It’s a floor.
Long-term rates at this level sit in the upper quarter of their entire historical range. The last time the 10-year spent extended time above 5% was the mid-2000s and briefly in late 2023. What makes today’s environment different is the context around it: inflation is still running hot relative to history, the real policy rate (the fed funds rate minus inflation) is elevated, and yet credit conditions have quietly moved from tight back to neutral over the past reading. Borrowing is getting easier in the credit markets, even as the price of that borrowing stays high. Those two things can coexist for a while, but they tend to resolve in one direction eventually.
Historically, when long-term rates have held this high for extended periods, businesses face a genuine recalculation on capital spending. The hurdle rate for any investment goes up. Projects that penciled out at 3% financing costs look different at 5%-plus. In past cycles, investors have paid close attention to how long these elevated-rate environments persist, because duration matters as much as the level. The longer rates stay here, the more refinancing pressure builds across corporate balance sheets.
Consumer sentiment is near historic lows even as markets price calm (VIX is subdued, the S&P trend remains intact, and technology is the one sector genuinely outperforming). That gap between Main Street anxiety and Wall Street positioning is one of the more important tensions in the current data set.
Bottom Line: A 5.31% 10-year yield is doing real work on the economy’s incentive structure, quietly raising the bar for every capital allocation decision made right now. The question that matters is whether rates stay here long enough to show up in hiring and investment data, or whether something breaks the ceiling before that happens.
Source: Federal Reserve Economic Data (FRED)
ON1010 Research is an independent publisher of economic education and is not a registered investment adviser, broker-dealer, or investment company. This content is for educational and informational purposes only and is not investment advice or a recommendation to buy, sell, or hold any security. Published under the publisher exemption recognized by Section 202(a)(11)(D) of the Investment Advisers Act of 1940 (Lowe v. SEC). Always consult a qualified financial professional before making any financial decision.
Free Research
The economy moves fast. We make sure you move faster.
Economic data, policy shifts, and market signals — delivered to your inbox.
Subscribe Free