
The 2-Year Treasury Is Quietly Drifting Lower. The Fed May Not Be Moving Anytime Soon.
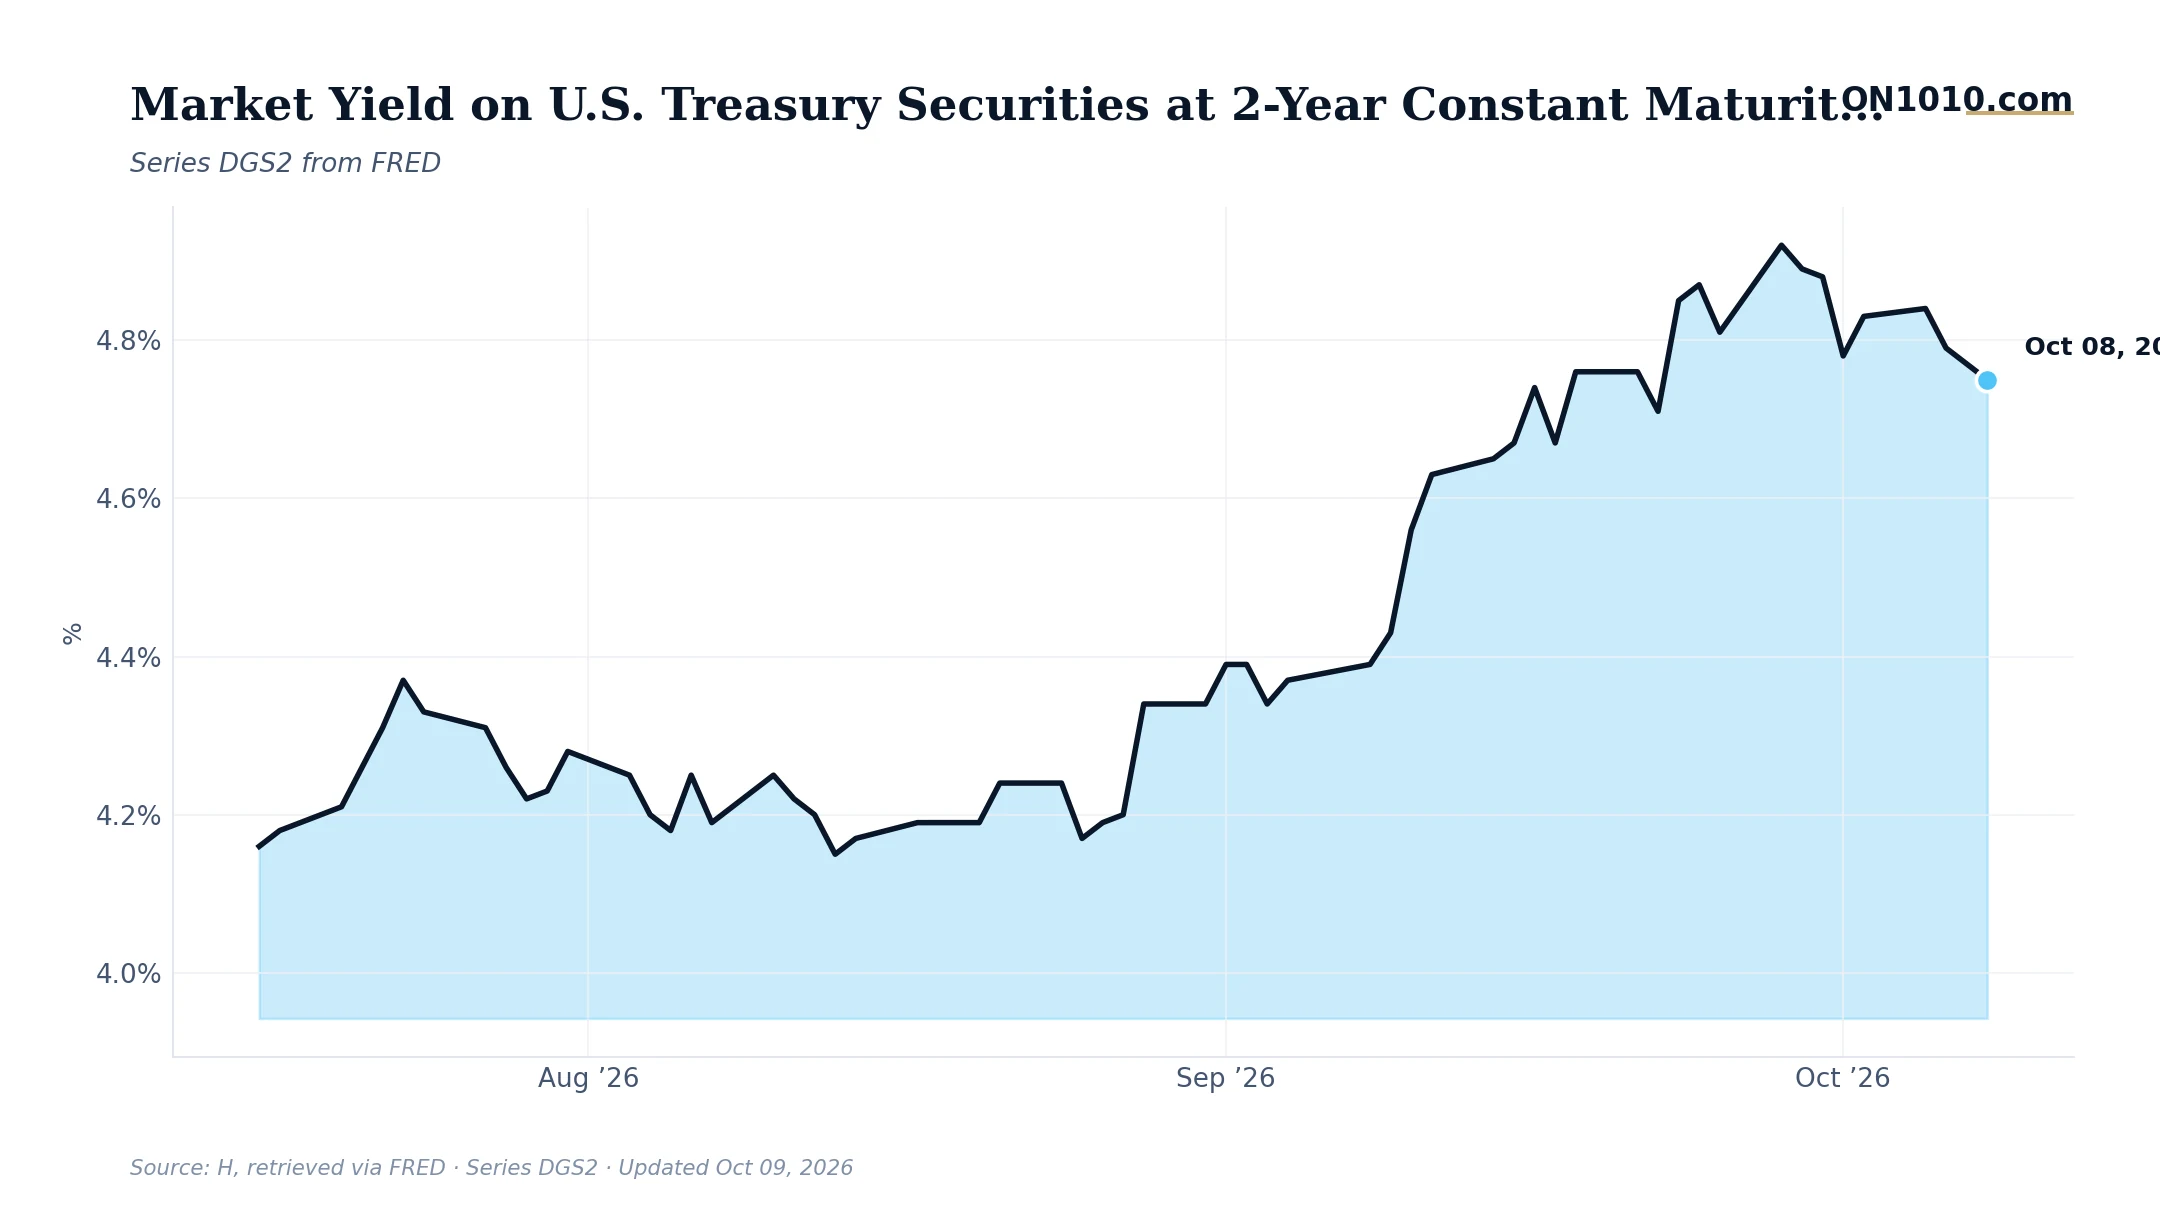
The 2-year Treasury yield slipped to 4.75% on October 8, continuing a gentle five-day slide from 4.84%. A 9-basis-point move in a week is small in absolute terms. The direction, though, tells a story worth paying attention to.
The 2-year yield is essentially the bond market’s best guess at where the Fed funds rate will average over the next two years. When it falls, markets are pricing in either cuts, a pause that stretches longer than expected, or growing concern that the economy will need relief. Right now, yields are sitting near historically elevated levels, which means monetary policy is still genuinely restrictive, the real policy rate remains firmly positive when measured against current inflation.
Here is the tension: inflation is still running hot by historical standards, the economy is growing at roughly its historical pace, and yet yields are softening. The bond market may be sniffing out a growth slowdown before it shows up in hard data. Consumer sentiment is near the bottom of its historical range, a reading that has historically resolved upward, but the path matters. Historically, when monetary policy is this restrictive and long-term rates are in their upper historical range, a new recession began within the next 12 months about 14% to 18% of the time. That is not a forecast; it is the base rate worth knowing.
In past cycles, a sustained drift lower in the 2-year yield has prompted businesses to revisit financing decisions, particularly for anything with a floating-rate component or near-term refinancing need. The question most worth asking: if rates are peaking here, how long does “higher for longer” actually last, and what does that do to capital allocation decisions already on hold?
Bottom Line: The 2-year yield is easing, but 4.75% is still historically high ground. The market is softening its rate expectations ever so slightly, and whether that reflects confidence or caution is exactly the debate that will drive decisions in boardrooms over the next six months.
Source: Federal Reserve Economic Data (FRED)
ON1010 Research is an independent publisher of economic education and is not a registered investment adviser, broker-dealer, or investment company. This content is for educational and informational purposes only and is not investment advice or a recommendation to buy, sell, or hold any security. Published under the publisher exemption recognized by Section 202(a)(11)(D) of the Investment Advisers Act of 1940 (Lowe v. SEC). Always consult a qualified financial professional before making any financial decision.
Free Research
The economy moves fast. We make sure you move faster.
Economic data, policy shifts, and market signals — delivered to your inbox.
Subscribe Free