
The Fed Is Hiking Again. The Interesting Part Is What It Says About Inflation.
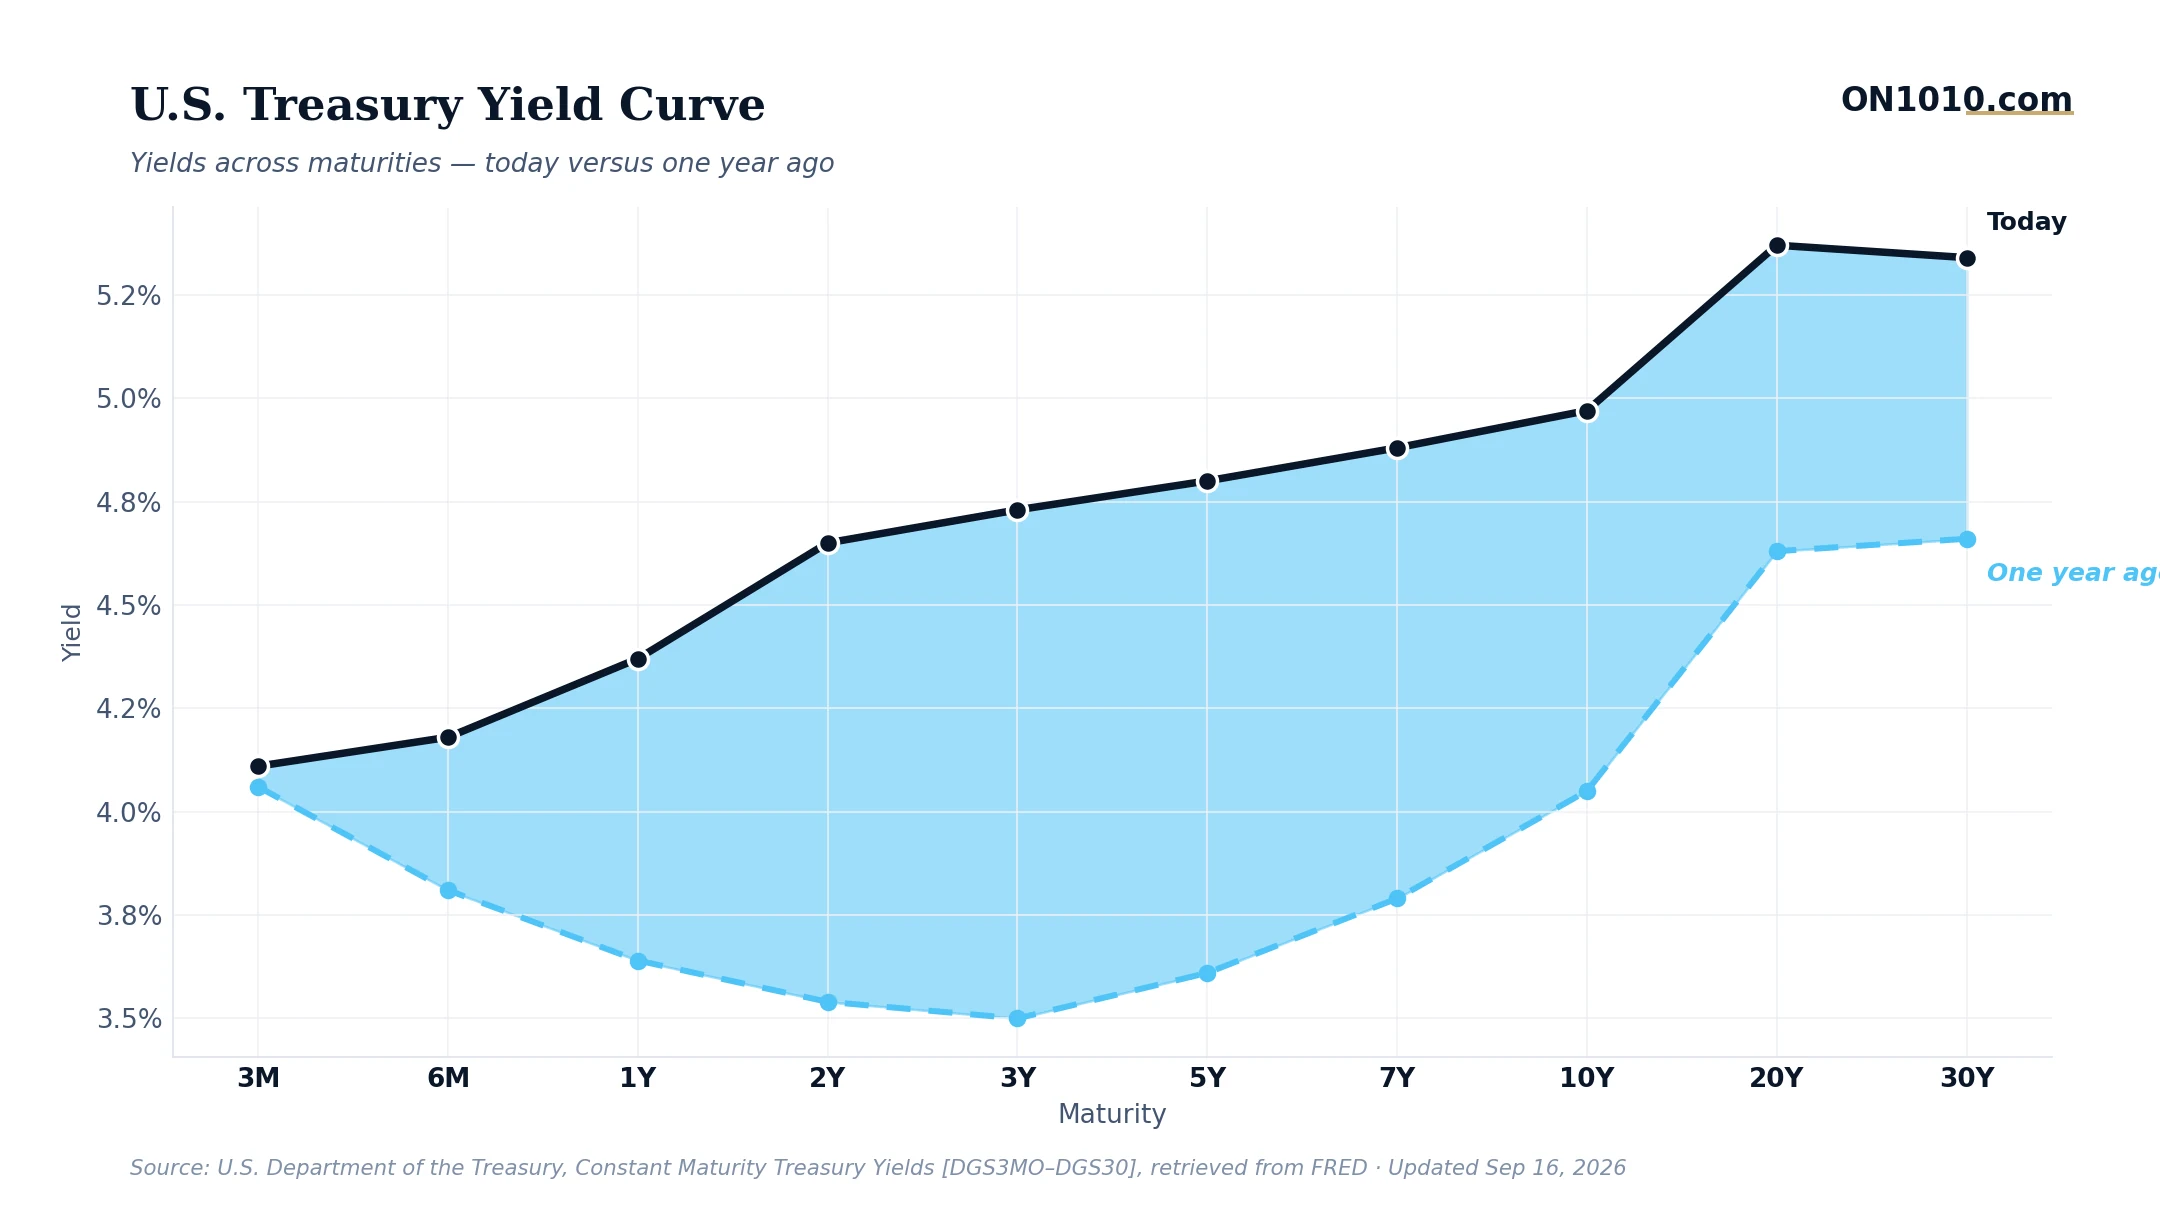
According to CNBC, the Federal Reserve raised interest rates Wednesday and signaled at least one more hike before year-end, bringing the federal funds target range to 3.75%-4.00%. The headline writes itself. The more interesting question is what this move reveals about where inflation actually stands.
Core inflation is running hotter than roughly nine out of every ten months in the historical record. The Fed paused rate hikes back in 2023 and spent most of 2024 and 2025 in a holding pattern that looked, to many observers, like victory. Restarting the cycle now suggests that victory was premature, or at least incomplete. Price pressures that were supposed to fade quietly have stayed stubbornly warm, and the Fed is responding to data, not the narrative.
Here is where it gets complicated. Long-term interest rates are already sitting in the upper quarter of their historical range, which means financial conditions are tightening from a position that was already elevated. Businesses that need to finance equipment, inventory, or expansion are paying more for that capital, and that cost goes somewhere: thinner margins, slower hiring, or both. Meanwhile, credit spreads in the bond market remain historically tight, signaling that professional investors see no immediate crisis of confidence in corporate creditworthiness. The economy is not breaking, but the cost of doing business is quietly rising.
Consumer sentiment is near a historic low, yet recession odds implied by similar growth readings are modest. Historically, when growth gauges sat near their long-run midpoints with inflation this elevated, recessions over the following twelve months were relatively rare. That is a base rate, not a guarantee, but it does push back against the most alarming interpretations of today’s move. What historically has mattered more in this setup is the margin picture: whether companies can pass higher costs through to prices or absorb them. When they cannot, hiring and investment slow before unemployment ever blinks.
Bottom Line: The Fed hiking again three years after its last increase is a clear signal that the inflation story is not finished. The relevant question for businesses and investors is where corporate margins are heading as borrowing costs rise on top of a financing environment that was already expensive.
Read more: CNBC Top News
ON1010 Research is an independent publisher of economic education and is not a registered investment adviser, broker-dealer, or investment company. This content is for educational and informational purposes only and is not investment advice or a recommendation to buy, sell, or hold any security. Published under the publisher exemption recognized by Section 202(a)(11)(D) of the Investment Advisers Act of 1940 (Lowe v. SEC). Always consult a qualified financial professional before making any financial decision.
Correction (September 25, 2026): An earlier version gave the new target range as 3.50%-3.75%. The FOMC statement of September 16, 2026 raised the range by 1/4 percentage point to 3.75%-4.00%.
Free Research
The economy moves fast. We make sure you move faster.
Economic data, policy shifts, and market signals — delivered to your inbox.
Subscribe Free