
The 2-Year Treasury Is Stuck in No Man’s Land
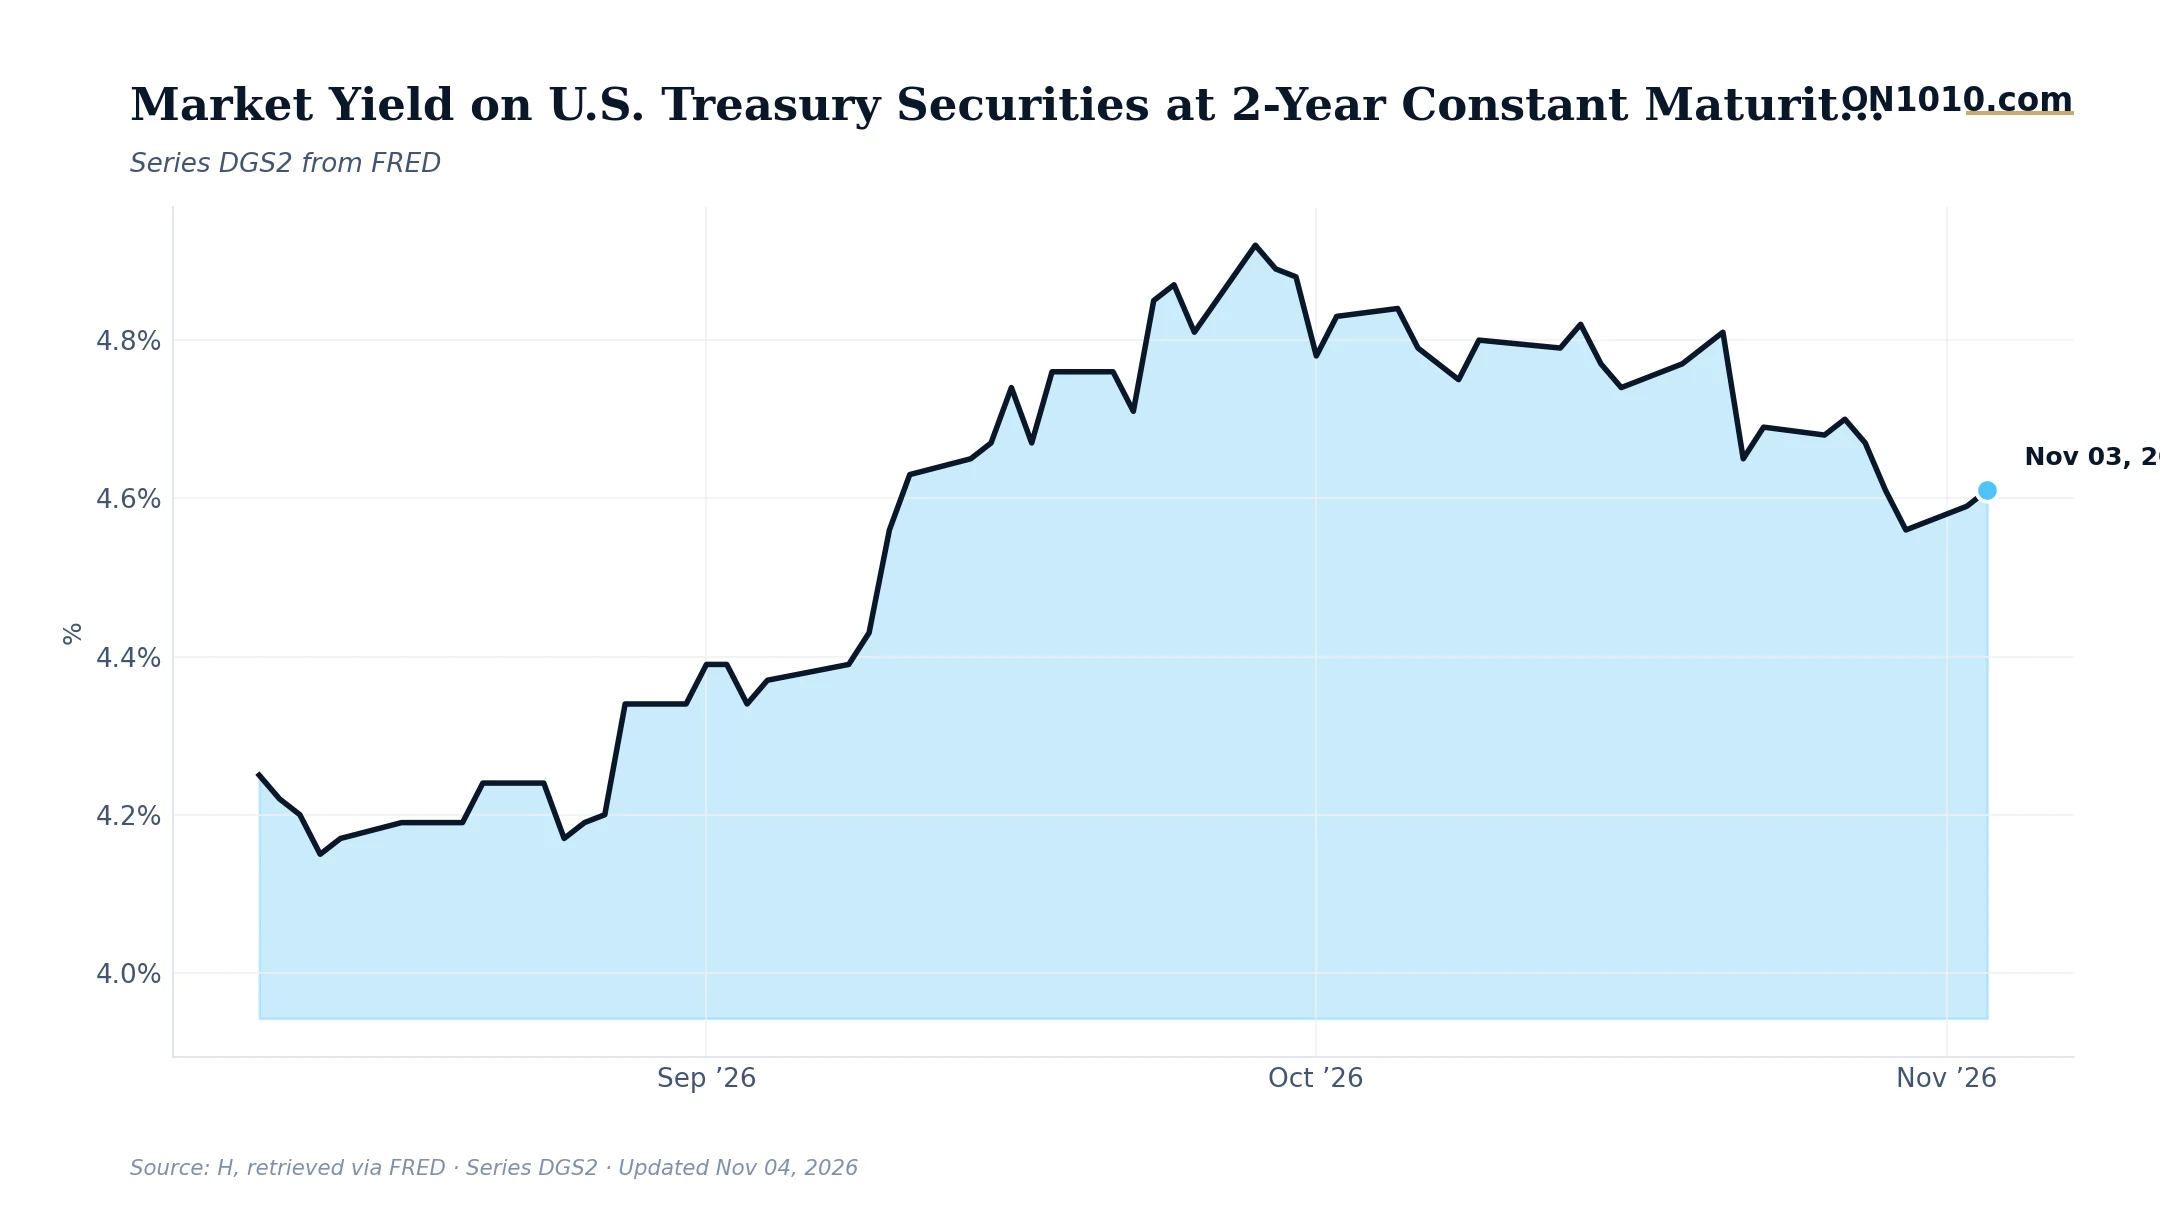
The 2-year Treasury yield closed at 4.61% on November 3, edging up from 4.59% the day before. The move itself is barely a rounding error. What’s interesting is where it’s sitting: after a brief dip toward 4.56% last week, yields are drifting back up, and the market’s implied message about Fed rate cuts is getting quieter by the day.
The 2-year yield is essentially a live poll on what bond traders think the Fed will do over the next 12 to 24 months. When it falls sharply, traders are pricing in cuts. When it rises, they’re walking those cuts back. The drift from 4.56% to 4.61% over the past week is a small but clear signal: the market is paring back its optimism about near-term easing. With core inflation running historically hot and the real policy rate sitting well above its historical norm, the Fed has limited room to pivot without risking a credibility problem.
That backdrop matters, because other gauges are sending a louder alarm. Credit spreads have widened into historically elevated territory. Consumer sentiment is near historical lows. The VIX just moved from neutral to elevated, a shift that has historically preceded softer economic conditions roughly one in five times over the following year. Defensive sectors, including consumer staples, healthcare, utilities, and real estate, are collectively beating the broader market by double digits over the past month. Equity markets often lead the economy by repricing quickly, and right now the rotation tells a cautious story that the 2-year yield hasn’t fully reflected.
Historically, when short-term yields stay elevated while credit spreads widen and equity markets rotate defensively, businesses have found financing costs sticky even as growth expectations soften. The question that tends to matter most in that environment: are profit margins wide enough to absorb higher borrowing costs, or will rising interest expense start compressing earnings before rate relief arrives?
Bottom Line: At 4.61%, the 2-year yield is telling you the Fed is on hold longer than many hoped. The more pressing question is whether corporate margins can hold up while the market waits.
Source: Federal Reserve Economic Data (FRED)
ON1010 Research is an independent publisher of economic education and is not a registered investment adviser, broker-dealer, or investment company. This content is for educational and informational purposes only and is not investment advice or a recommendation to buy, sell, or hold any security. Published under the publisher exemption recognized by Section 202(a)(11)(D) of the Investment Advisers Act of 1940 (Lowe v. SEC). Always consult a qualified financial professional before making any financial decision.
Free Research
The economy moves fast. We make sure you move faster.
Economic data, policy shifts, and market signals — delivered to your inbox.
Subscribe Free