
The Fed’s Inflation Problem Has a New Complication: The Market Already Sees It
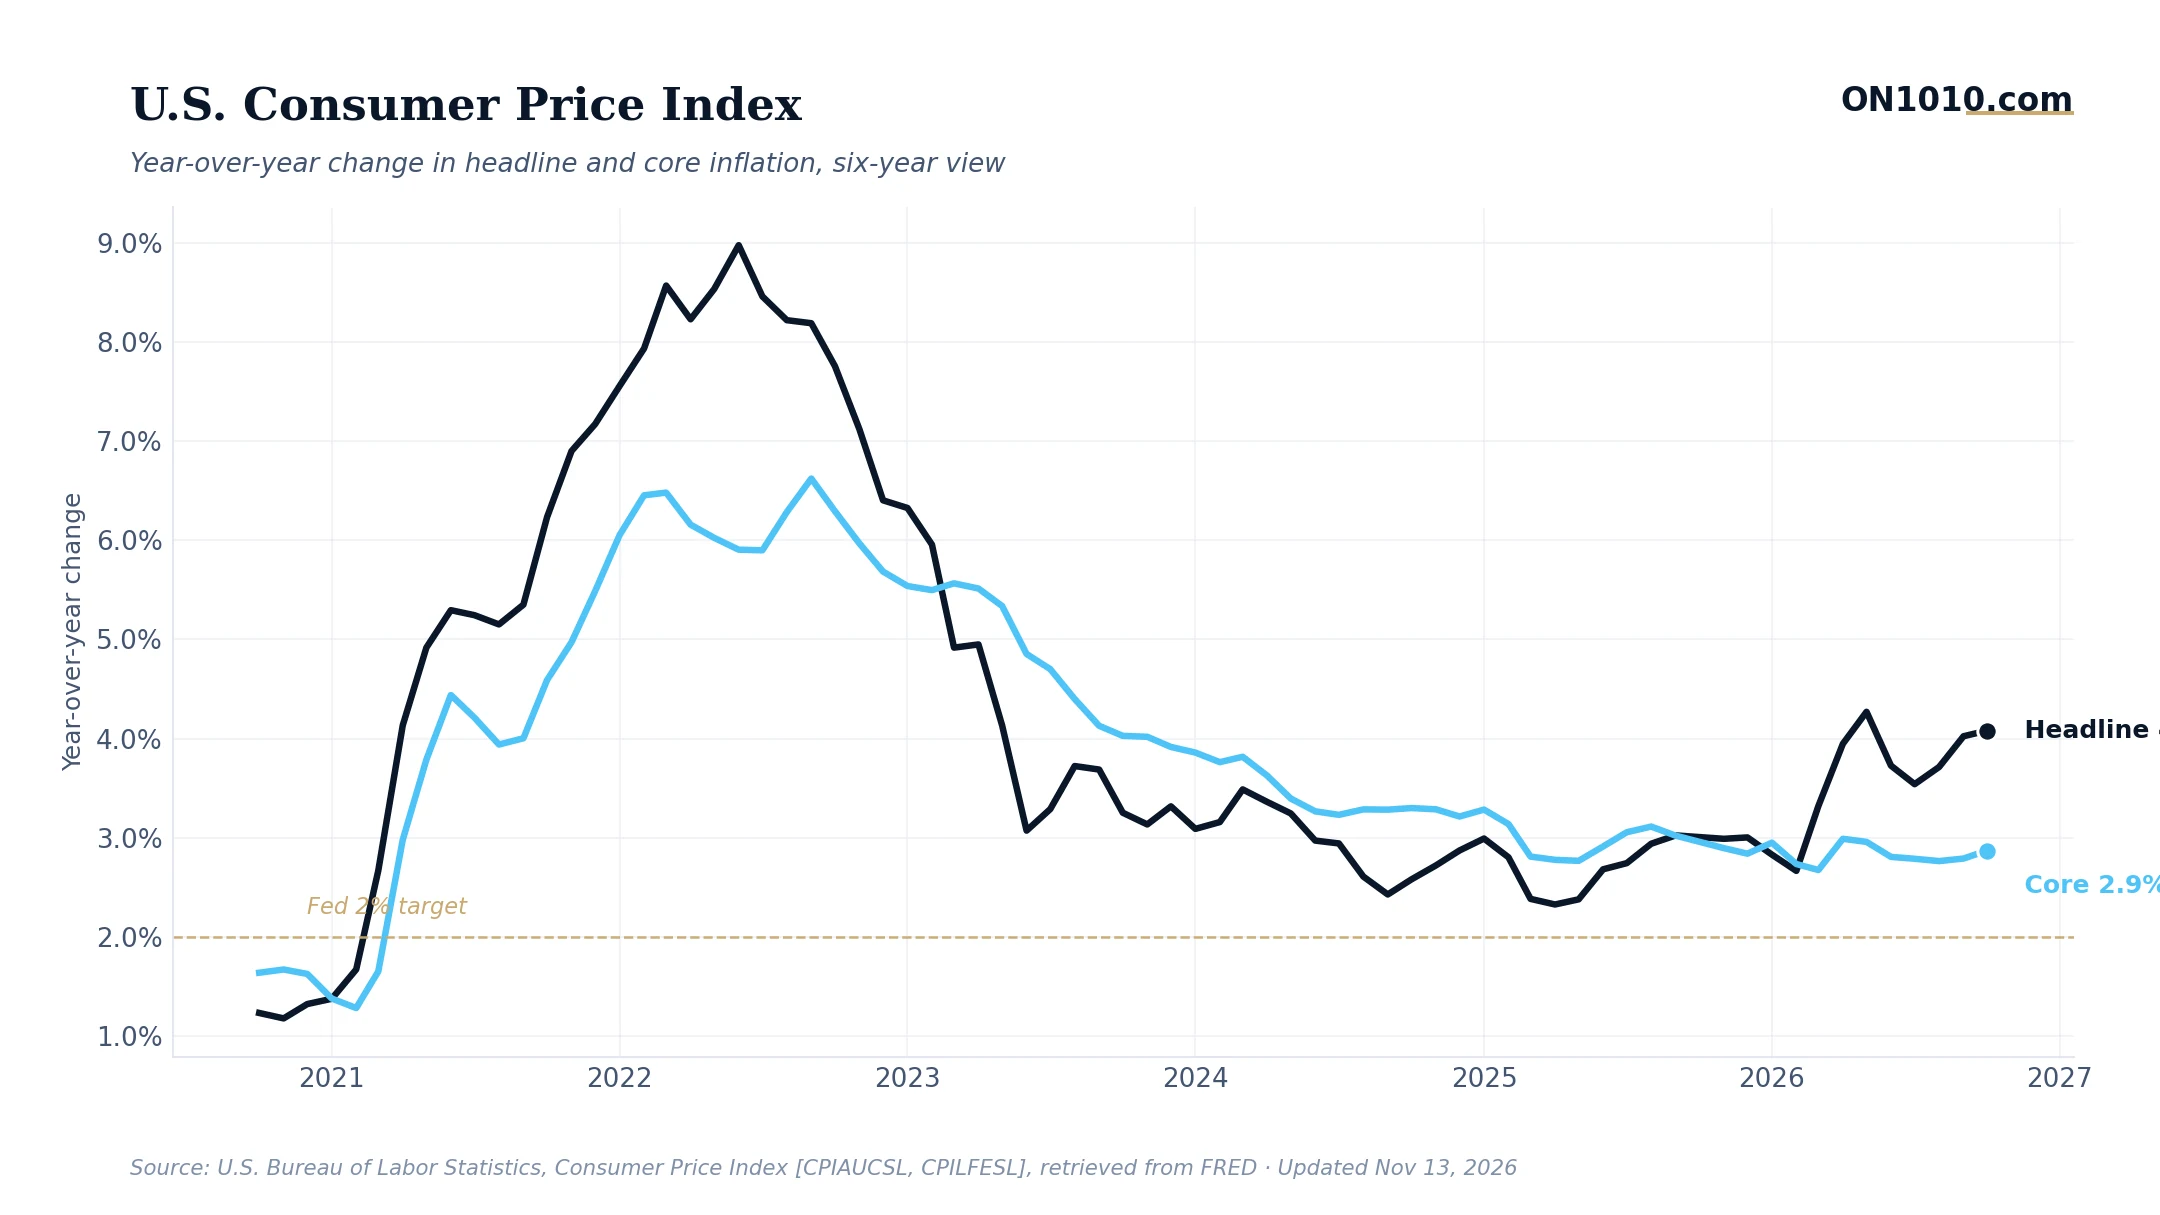
According to CNBC, Chicago Fed President Austan Goolsbee told the network that the central bank “has definitely got work to do” on inflation, signaling that the latest data has rattled at least one policymaker enough to put further action back on the table. The interesting part is not what Goolsbee said. It is what the broader dashboard is already telling us.
The CPI index level sits at 337.5, with core inflation running at readings higher than roughly nine of every ten months in the historical record. That is not a blip. That is a persistent condition. Meanwhile, long-term interest rates have recently shifted from steady to rising, credit spreads are wide and widening, and defensive sectors are beating the broader market by over seven percentage points in the past month. When money rotates hard into Consumer Staples, Health Care, and Utilities while Technology bleeds, the market is not speculating about a soft landing. It is hedging against something harder.
This is where the balance sheet story matters. The Fed’s real policy rate is already high relative to history, which means monetary policy is genuinely restrictive on paper. But inflation running this hot simultaneously raises the question of whether “restrictive” is actually doing enough work. Businesses facing both elevated borrowing costs and sticky input costs are being squeezed on two sides of the margin equation. When margins compress, hiring and investment decisions follow. That sequence tends to show up in the economy later, long after the market has already repositioned.
Historically, investors have treated periods where restrictive monetary policy coincided with persistently high inflation as inflection points, watching credit conditions and long-term yield direction closely as the leading signals of whether policy would tighten further or hold. Both of those signals just moved in a direction that warrants attention. Past performance does not predict future results, but the setup is one the market appears to be taking seriously.
Bottom Line: Goolsbee’s comment is the Fed saying out loud what the bond market, credit spreads, and sector rotation have been telegraphing for weeks. Inflation that refuses to come down in a restrictive-rate environment is a harder problem than inflation that just needs time.
Read more: CNBC Top News
ON1010 Research is an independent publisher of economic education and is not a registered investment adviser, broker-dealer, or investment company. This content is for educational and informational purposes only and is not investment advice or a recommendation to buy, sell, or hold any security. Published under the publisher exemption recognized by Section 202(a)(11)(D) of the Investment Advisers Act of 1940 (Lowe v. SEC). Always consult a qualified financial professional before making any financial decision.
Free Research
The economy moves fast. We make sure you move faster.
Economic data, policy shifts, and market signals — delivered to your inbox.
Subscribe Free