
Versant Beat the Number. The Harder Question Is Whether the Number Still Matters.
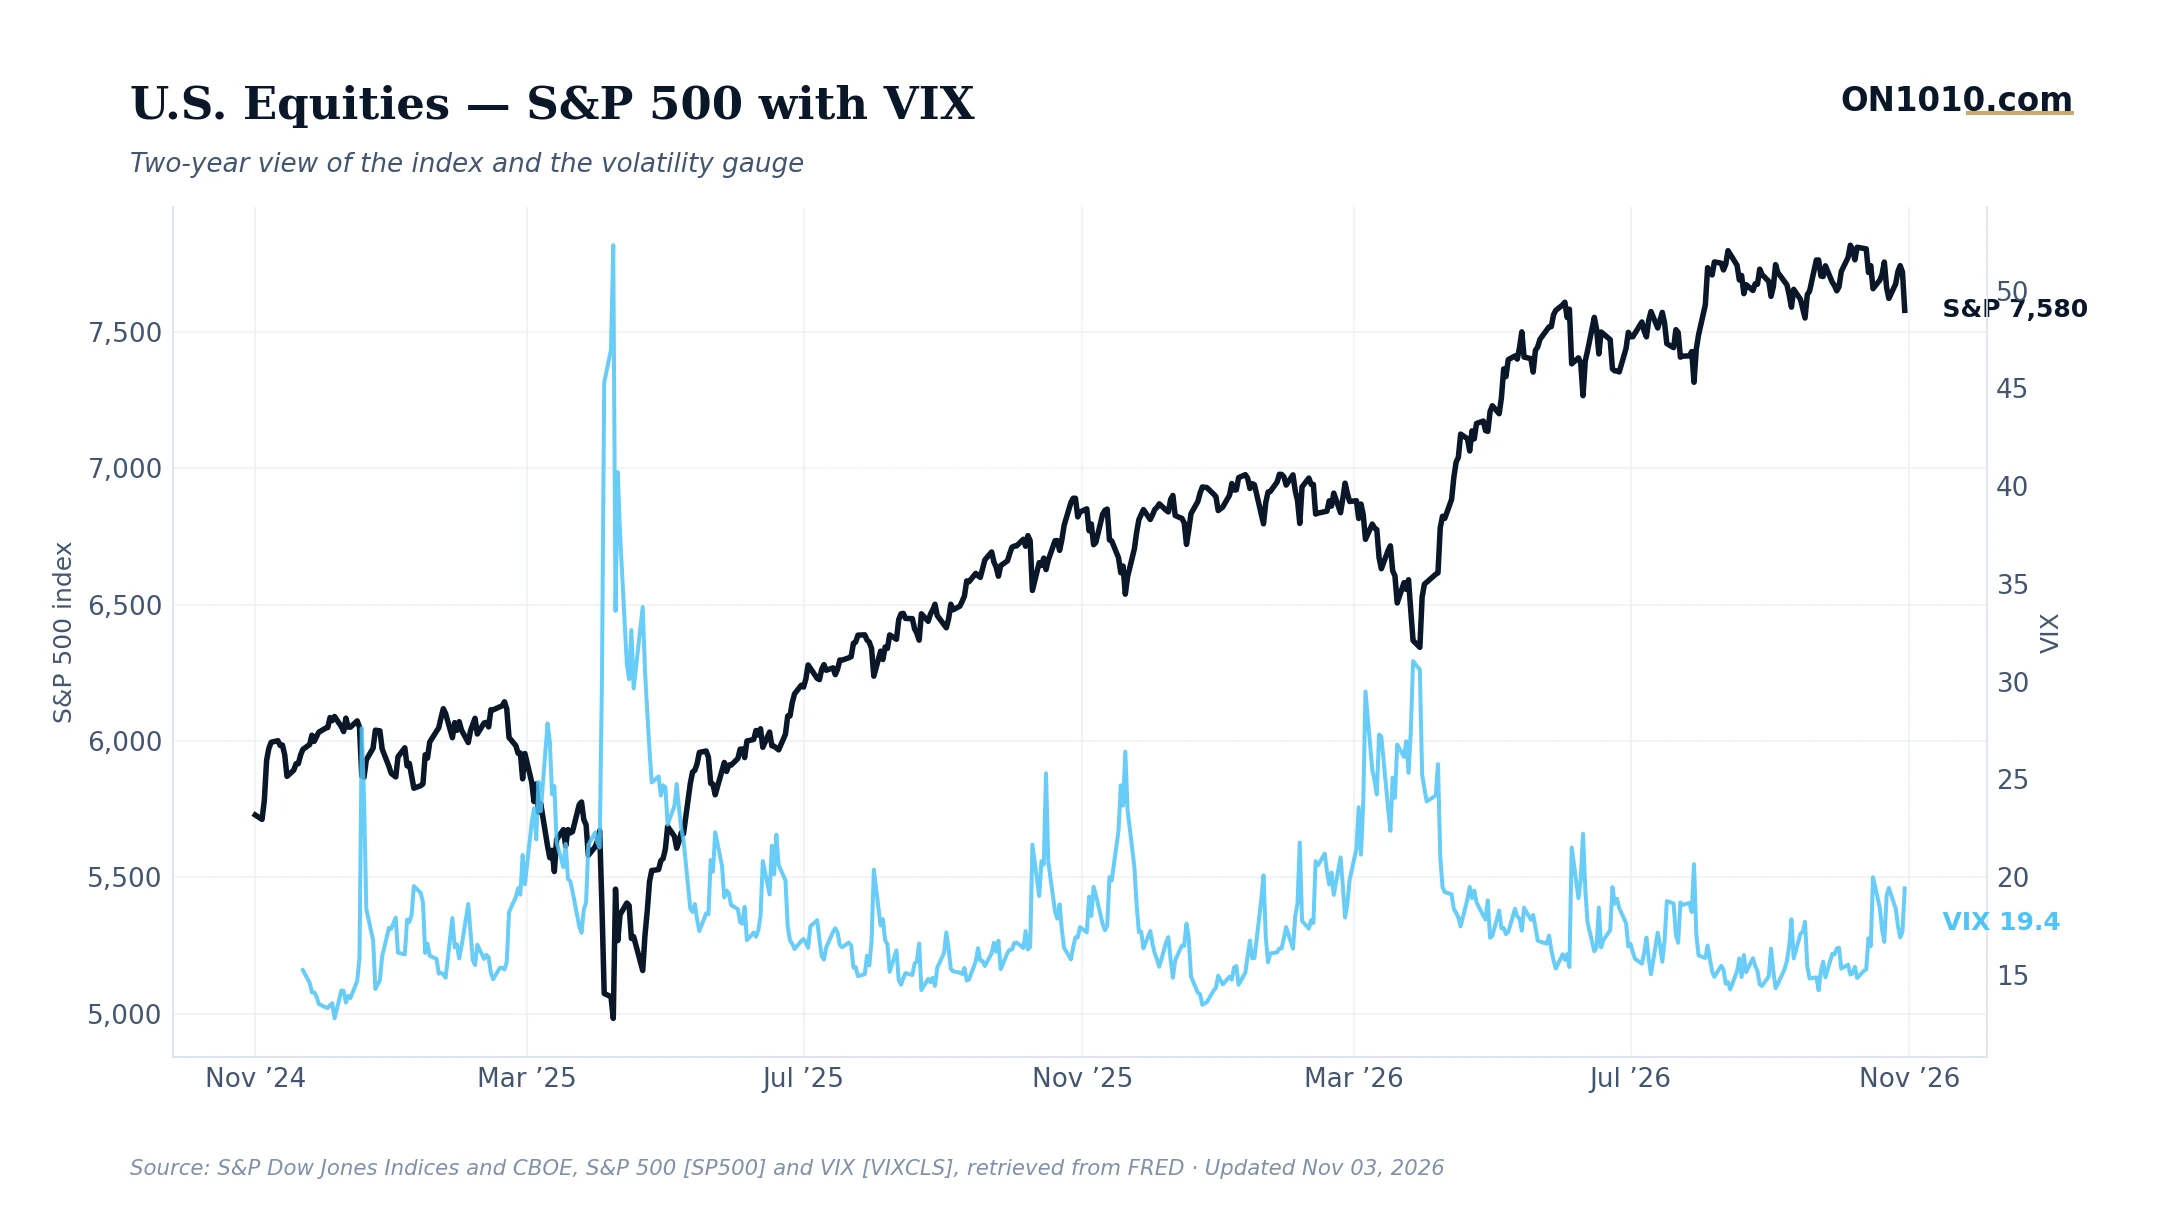
According to CNBC, Versant posted third-quarter earnings that topped Wall Street expectations and reaffirmed full-year guidance, with digital platforms cited as the primary growth driver.
The beat is real. But zoom out, and the backdrop it landed in is worth understanding.
Digital platform businesses tend to carry high gross margins and low marginal costs. Once the infrastructure is built, each additional user or dollar of revenue flows through at a much better rate than traditional businesses. When that dynamic is working, it shows up in expanding margins, which historically leads hiring and investment decisions by several quarters. Versant’s ability to reaffirm guidance in an environment where credit spreads are wide and consumer sentiment is sitting near historical lows suggests the margin engine is still running. That is the part worth watching more than the headline beat.
The broader context, though, adds friction. Institutional money has been rotating hard into defensive sectors over the past month, with technology and communication services notably underperforming. High-margin digital businesses sit squarely in the crosshairs of that rotation, regardless of their fundamental story. And with monetary policy still restrictive and long-term rates historically elevated, the cost of capital remains a real headwind for growth-oriented companies, even ones executing well.
Historically, investors have used earnings beats combined with guidance holds as a signal that management has reasonable visibility into near-term demand, which carries more weight during uncertain periods than in calm ones. The question Versant’s quarter raises is whether digital platform revenue is durable enough to hold through tighter consumer spending, or whether it is benefiting from a pocket of the economy that has been more insulated than the aggregate numbers suggest.
Bottom Line: Beating expectations is easier when expectations have been revised down. The real story is whether Versant’s margins are expanding or just holding, and in this environment, holding is a better answer than most.
Read more: CNBC Top News
ON1010 Research is an independent publisher of economic education and is not a registered investment adviser, broker-dealer, or investment company. This content is for educational and informational purposes only and is not investment advice or a recommendation to buy, sell, or hold any security. Published under the publisher exemption recognized by Section 202(a)(11)(D) of the Investment Advisers Act of 1940 (Lowe v. SEC). Always consult a qualified financial professional before making any financial decision.
Free Research
The economy moves fast. We make sure you move faster.
Economic data, policy shifts, and market signals — delivered to your inbox.
Subscribe Free