
The Morning Bell August 17, 2026
China Is Slowing. The Bond Market Already Knew.
China Is Slowing. The Bond Market Already Knew.
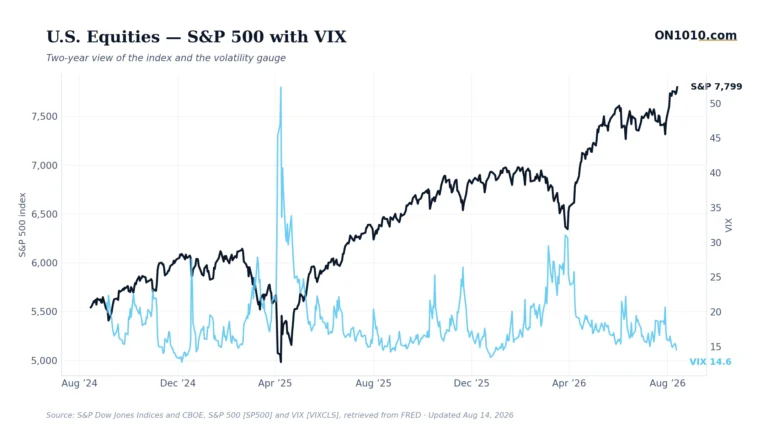
The S&P 500 closed at 7,798.99 Thursday. The VIX sat at 14.57, well below its 20-day average of 16.65. By every surface read, markets look calm. But gold closed at $4,410.30, up $46.70 on the session, while the dollar slipped to 99.74. When calm mark
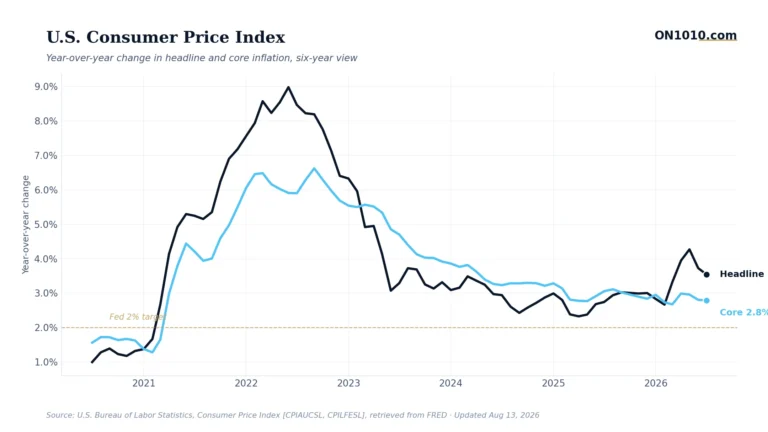
Yesterday’s CPI report delivered something genuinely unusual: annual core inflation fell to 1.93%, the first time it has printed below 2% in years, according to the Data Wire. That should be a clean win for the Fed.
Here is the honest tension heading into Wednesday morning: the July CPI report prints today, and Wall Street is expecting a modest monthly increase. That sounds reassuring. But the more important question is whether the headline number tells you anyt
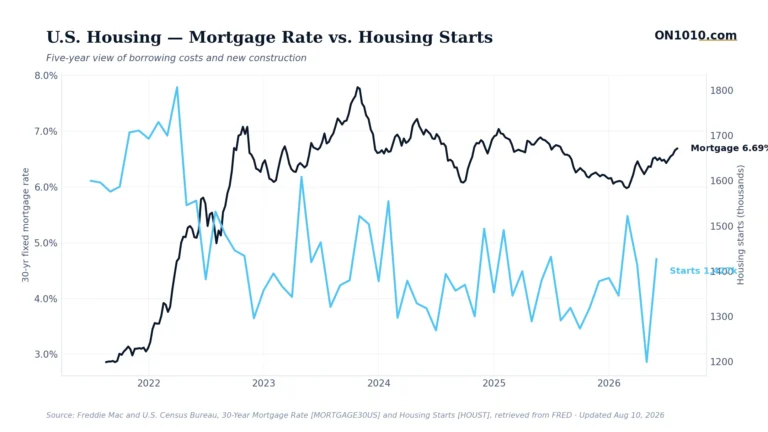
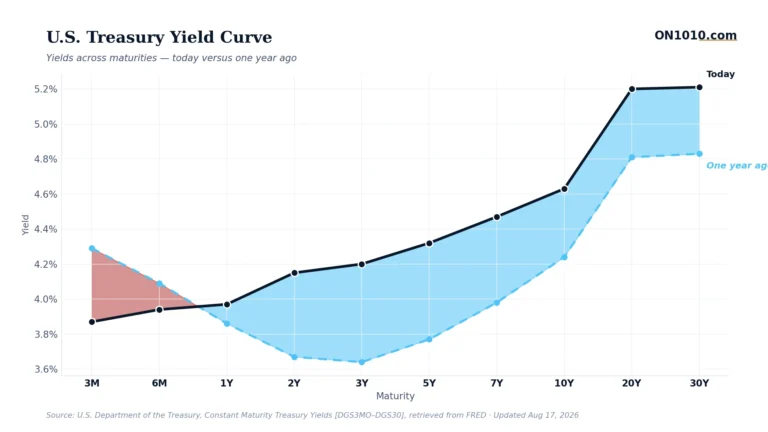
The 10-year Treasury yield sits at 4.69% this Monday morning. That is 94 basis points above the Fed’s upper target rate of 3.75%. For most of the economy, that gap is just a number. For housing, it is the ballgame.
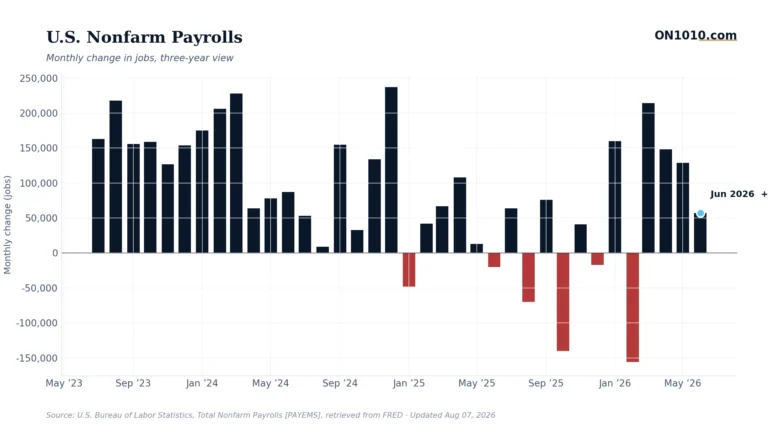
The number everyone is watching prints this morning: July nonfarm payrolls. Economists expect just 83,000 new jobs, with the unemployment rate holding at 4.2%. That is a soft forecast, and the market has already priced in a cautious read.
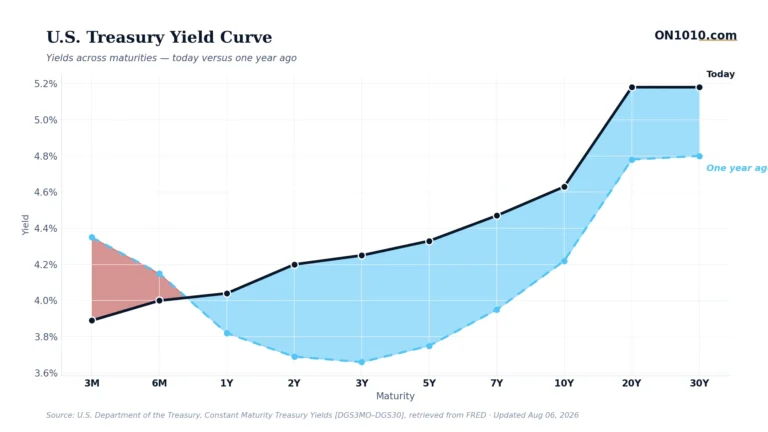
Gold hit $4,334.80 yesterday, up 2.10% in a single session. That is a big move for a metal that usually creeps. Meanwhile, the 10-year Treasury yield sits at 4.63%, the 2-year at 4.20%, and the spread between them is a calm 45 basis points positive.
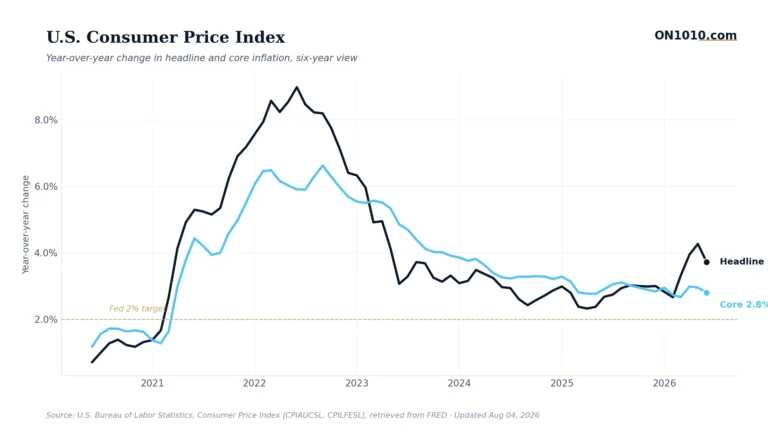
Here is the puzzle sitting in the data this morning. Core inflation is running hotter than roughly nine out of every ten months in the historical record, and a fresh manufacturing survey just said inflation worries among purchasing managers have grow
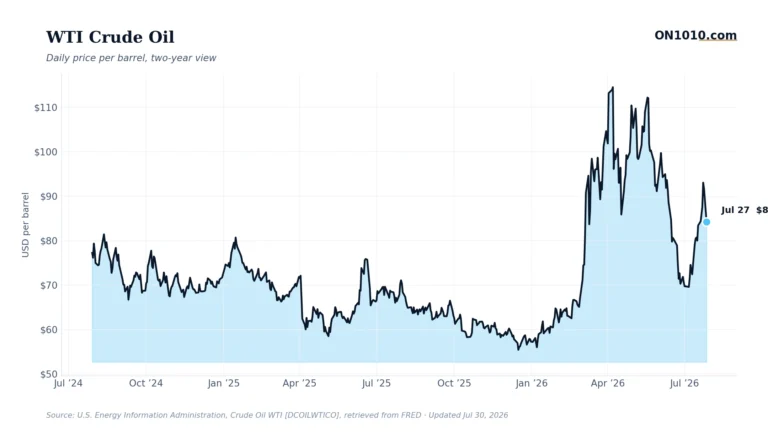
Oil just dropped nearly 6% in a single session. Most of the coverage will focus on Iran. The more interesting story is what a $79 oil price means for an inflation gauge that is still running hotter than roughly nine of every ten months on record.
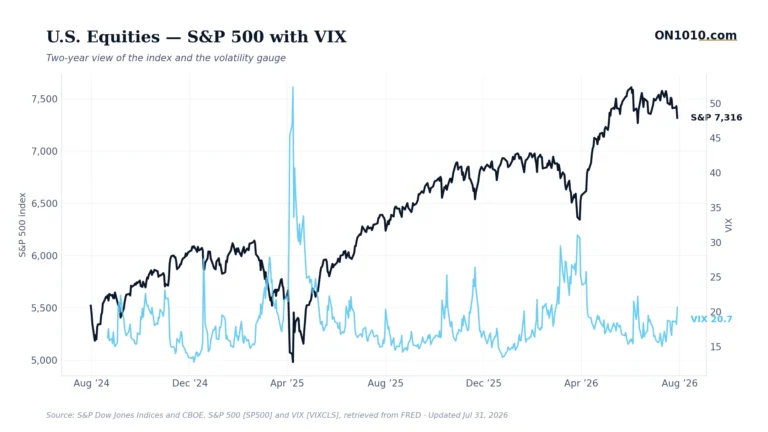
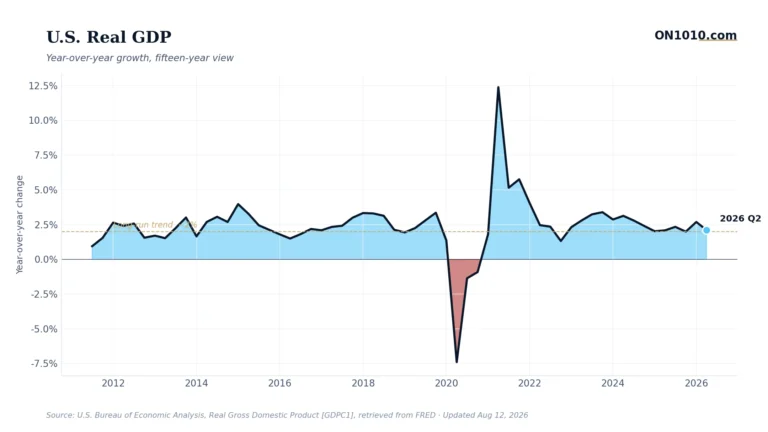
The headline GDP number is in, and at first glance it looks like a soft but survivable quarter. The twist is that markets and sectors are quietly disagreeing with each other about what it means.
Meta fell nearly 9% yesterday. Microsoft jumped 8% after the bell. Same theme, same bet, wildly different outcomes. When the biggest trade in markets stops moving as one block, that is usually worth paying attention to.
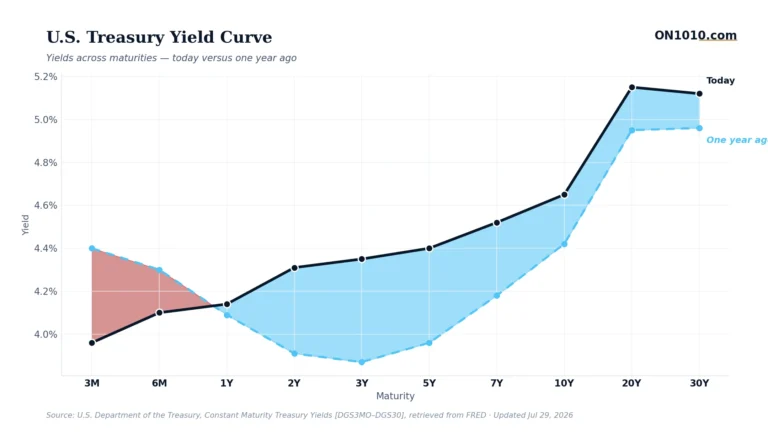
The Fed kept rates at 3.5% to 3.75% yesterday. That decision is now yesterday’s news. The harder question starts this morning: can the economy actually grow its way through a 4.65% ten-year yield?
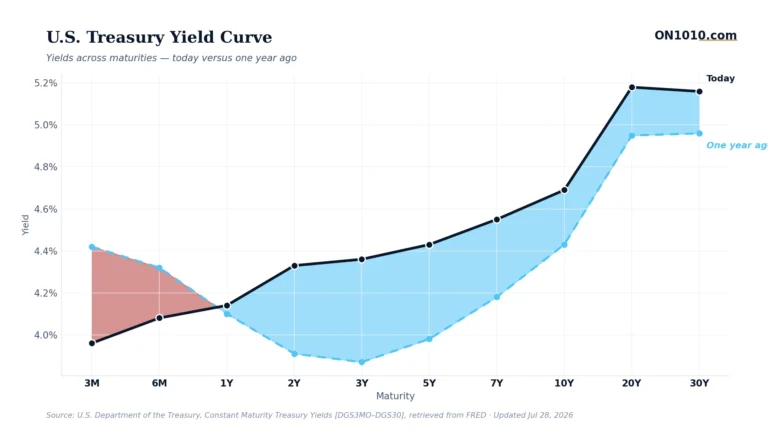
Everyone is watching the Fed’s rate decision this afternoon. But the more interesting question isn’t what the Fed does today. It’s what the housing market has already been doing while the Fed deliberates.
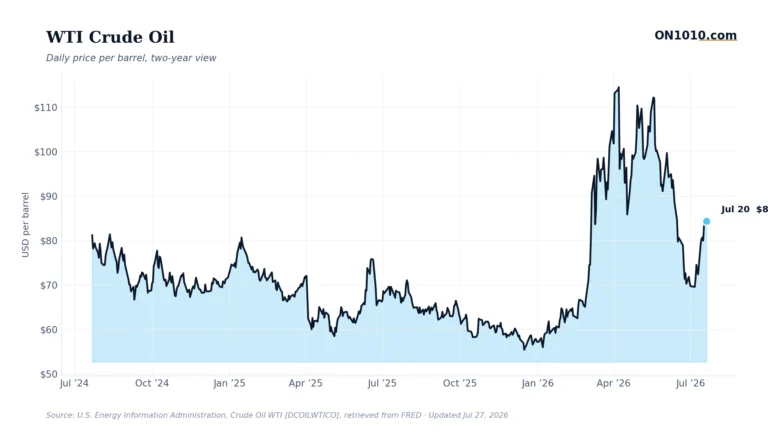
Crude oil fell $6.89 to $82.42 a barrel on Friday, a 7.7% single-session drop. Gasoline followed, sliding 8.6% to $3.10 a gallon. The headline reads like relief for consumers. The question worth asking Monday morning is whether the market is pricing
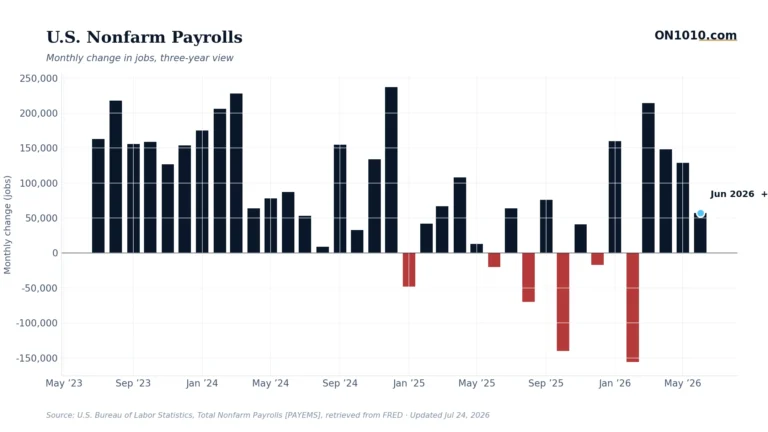
Here is the puzzle heading into the final session of the week: jobless claims just hit their lowest recent reading, yet institutional money is quietly rotating away from growth and into defense. The economy and the market are sending different signal
ON1010 Research is an independent economic publication. The content on this site is for educational and informational purposes only.
ON1010 Research is not a registered investment advisor, broker-dealer, financial planner, accountant, or attorney. Nothing on this site, in our newsletters, or in any other communication from ON1010 constitutes personalized investment, financial, tax, legal, or accounting advice, an offer to buy or sell any security, or a solicitation of any offer to buy or sell any security. No fiduciary or advisory relationship is created by viewing, subscribing to, or otherwise interacting with our content.
Information published on this site is derived from sources we believe to be reliable, including primary government data feeds (Federal Reserve, BLS, BEA, Treasury, EIA, Census). We make no representation or warranty as to its accuracy or completeness, and disclaim all liability for any loss arising from reliance on it. Past performance is not indicative of future results. Forward-looking statements, scenarios, and economic outlooks reflect opinions as of the date of publication and may change without notice. Markets involve risk, including potential loss of principal.
Before making any investment decision, consult a qualified financial professional who is familiar with your individual circumstances. By using this site you agree to our Terms of Service and Privacy Policy.
© 2026 ON1010 Research. All rights reserved.